A Mortgage Broker who knows Bayside as well as you do
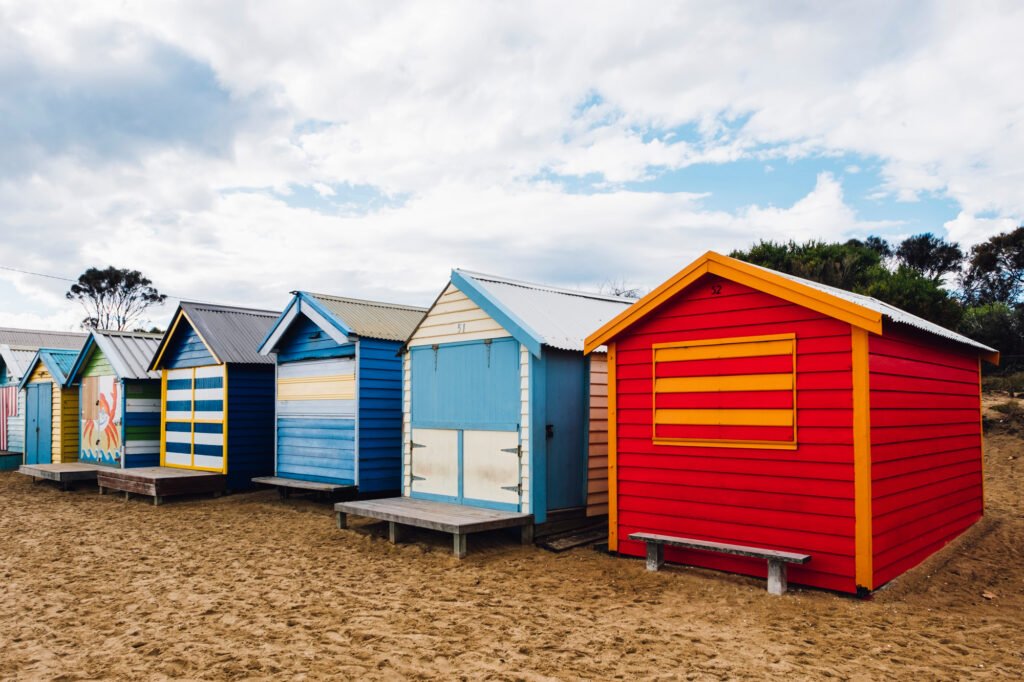
From the bathing boxes at Brighton to the cliff walk at Beaumaris, we broker home, investment, SMSF and commercial loans for professionals and families across Brighton, Hampton, Sandringham, Black Rock, Beaumaris and Mentone.
Local lending, built around how Bayside actually buys
Bayside Melbourne isn’t one market — it’s several, sitting side by side. Brighton and Hampton skew toward period homes, renovations and knockdown-rebuilds along the tree-lined streets off Church Street and Hampton Street. Sandringham and Black Rock mix beachside apartments with family homes close to the Bay Trail. Beaumaris and Mentone bring a slightly more relaxed, family-first buyer, often trading a larger block for proximity to the water and the Beaumaris Concourse shops.
We work across all of it, which means we’re not learning your suburb while we’re trying to get your loan approved. We already know which lenders back period-home renovations in Brighton East, which are comfortable with SMSF purchases in Mentone, and which will move fast enough for a competitive Black Rock auction.
Bayside Melbourne by the numbers
A snapshot of who’s living, buying and building across Bayside right now — the numbers behind why lending here looks the way it does.
106,118
City of Bayside population, 2024
40-49
Largest resident age bracket
0.6%
Average annual population growth to 2050
$1.4M–$3.3M
Typical house price range across the 7 suburbs
Population by suburb (2021 Census)
- Brighton — 23,252 (largest of the seven)
- Brighton East — 16,757
- Beaumaris — 13,947
- Hampton — 13,518
- Sandringham — 10,926
- Black Rock — 6,389
Fastest-growing suburbs, 2016–2021
- Sandringham — +6.7% (unit and townhouse development driving growth)
- Brighton East — +4.7%
- Beaumaris — +4.5%
Household profile
- Dominant household type: young and established families with children
- Bayside is largely built out, so growth here is steady and incremental rather than rapid — well suited to long-hold, capital-growth lending strategies
| Suburb | Median house price | Houses sold, past 12 months |
|---|---|---|
|
Brighton |
$3.0M – $3.3M |
~275–350 |
|
Brighton East |
$2.08M – $2.2M |
~200–280 |
|
Hampton |
~$2.49M |
~150 |
|
Black Rock |
~$2.48M |
~65 |
|
Sandringham |
~$2.4M |
~100 |
|
Beaumaris |
~$2.06M |
~180 |
|
Mentone |
~$1.44M |
~135 |
Data current as of August 2026. Source: CoreLogic property data via Your Investment Property and Jellis Craig suburb reports. Property prices and sales volumes change regularly — figures shown here are indicative and should be confirmed against current listings before relying on them.
Blocks across established Bayside streets typically run 500–650m², with many original quarter-acre allotments having been subdivided over the past two decades — a key reason knockdown-rebuild and dual-occupancy construction lending comes up so often in this area.
Average home loan sizes
Victoria’s average new owner-occupier home loan sits at $675,000 (ABS Lending Indicators, March 2026 quarter). Bayside runs well above that, reflecting the suburb’s higher entry prices and typically larger deposits or equity contributions from upgraders and downsizers.
| Suburb | Median house price | Estimated average home loan* |
|---|---|---|
|
Brighton |
~$3.15M |
~$2.21M |
|
Brighton East |
~$2.14M |
~$1.50M |
|
Beaumaris |
~$2.06M |
~$1.44M |
|
Bayside region average (7 suburbs) |
~$2.31M
|
~$1.62M |
*Estimated using each suburb’s median house price and a typical 70% loan-to-value ratio (30% deposit or equity), reflecting the upgrader- and equity-rich buyer profile common across Bayside. This is illustrative only — actual loan size depends on your deposit, existing equity and borrowing capacity. Get a personal borrowing power assessment for an exact figure.
Well-regarded local schools
- Brighton Grammar, Firbank Grammar & Haileybury (independent)
- Brighton Secondary College & Sandringham College (state)
- Hampton Primary, Sandringham Primary & Beaumaris Primary (state primary)
Landmarks locals love
- Brighton Bathing Boxes & Dendy Street Beach
- Church Street, Brighton — shopping and dining strip
- Bay Street, Beaumaris & Hampton Street village
- Half Moon Bay and the Beaumaris cliff-top walk to Table Rock Point
Sources: City of Bayside population and forecast data, profile.id / forecast.id (2024); ABS Census of Population and Housing 2016 & 2021; CoreLogic suburb data via Your Investment Property and Jellis Craig suburb reports (2026); ABS Lending Indicators, March quarter 2026 (Victoria average loan size). Figures are indicative and change regularly — ask us for the latest data on a specific suburb.
Lending structures that suit Bayside buyers
Renovation & Construction Finance
Bayside’s older housing stock along streets like New Street, Were Street and South Road means renovation and knockdown-rebuild lending comes up constantly. We structure progress-draw construction loans and renovation finance so funds release in line with your build, not your stress levels.
SMSF Property Lending
Bayside professionals with substantial super balances often look to SMSF lending for investment purchases in Mentone or Black Rock. We assess fund serviceability and Limited Recourse Borrowing Arrangement structuring before you go house-hunting, not after.Debt Recycling & Offset Strategy
With strong equity built up along the Beaumaris and Sandringham coastline, many clients use offset accounts and debt recycling structures to convert home loan debt into deductible investment debt over time, in step with their accountant.A recent Bayside scenario
Extending a Hampton home for baby number two
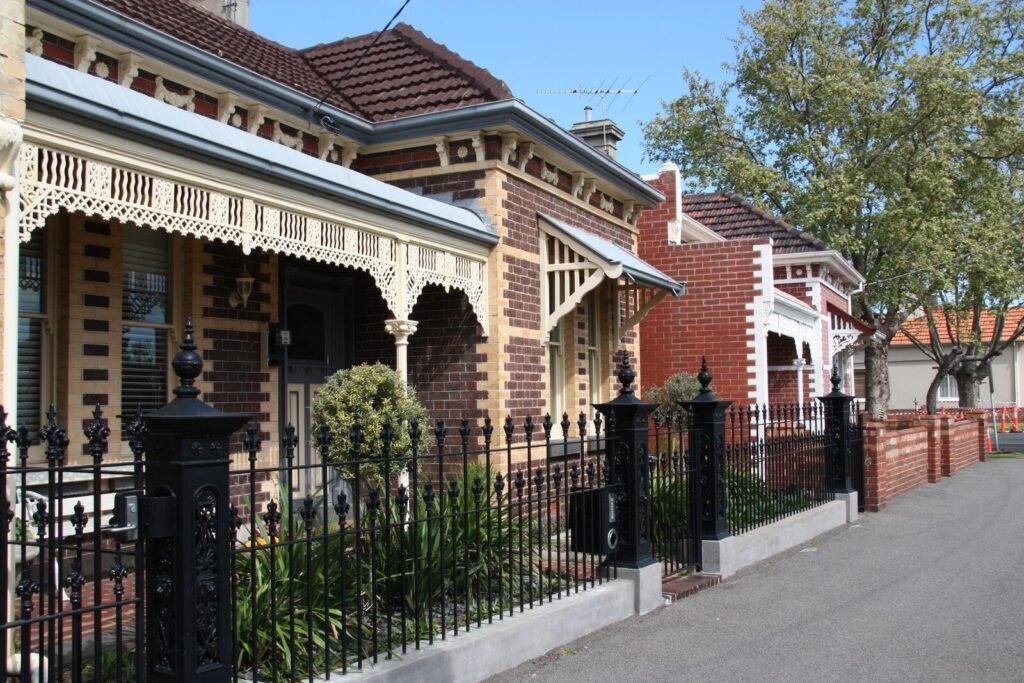
A professional couple in their early 40s came to me owning their Hampton home outright. Their eldest was already settled into the local primary school, and with a second baby on the way, their three-bedroom home suddenly felt tight — they needed a nursery and a bit more breathing room, without leaving the street their son already knew as home.
Rather than draining their savings or refinancing the whole property, we structured a construction loan against their equity, with their existing savings sitting safely in a linked offset account instead of being swallowed by the build. We also set the loan to interest-only for the length of construction, so their repayments stayed manageable while they were juggling a renovation, a newborn and full-time work.
Once the build was finished, the loan reverted to standard principal and interest — and they moved from a squeeze to a home that actually fit their family.
Bayside Melbourne home loan FAQs
What makes a mortgage broker useful for Bayside Melbourne buyers specifically?
Bayside suburbs like Brighton, Hampton and Beaumaris carry a mix of established period homes, renovation projects and premium new builds, which lenders price and assess differently. Working Bayside regularly means knowing which lenders value period homes on smaller Sandringham or Black Rock blocks accurately, which are comfortable with knockdown-rebuild lending in Brighton East, and where the best rates sit for professionals with strong but complex incomes.
Can I use an SMSF to buy an investment property in Bayside?
Yes. SMSF lending is a common structure for Bayside professionals building long-term wealth, particularly for investment purchases in Mentone or Black Rock. It requires a Limited Recourse Borrowing Arrangement and specific lender criteria, so it’s worth a proper assessment of your fund’s serviceability before you make an offer.
Is debt recycling worth considering for Bayside homeowners?
It can suit homeowners with meaningful equity in properties across Brighton, Hampton or Sandringham who want to convert non-deductible home loan debt into deductible investment debt over time. It isn’t right for everyone, so it’s usually discussed alongside your accountant as part of a broader wealth strategy.
How much deposit do I need to buy in Brighton or Hampton?
Most lenders want a minimum 10 to 20 percent deposit to avoid or minimise Lenders Mortgage Insurance, though the right figure depends on the property type, your income structure and whether you’re buying as an owner-occupier or investor. A borrowing power assessment gives you an exact figure before you start inspecting.
Ready to talk Bayside lending?
Tell us a little about what you’re looking to do — buy, build, renovate or invest — and we’ll come back with the lending structure that actually fits.