Commercial property loans
When the numbers alone don't tell your story, I make sure the lender sees the rest
Business financials rarely fit neatly into a lender’s standard checklist: net profits, addbacks, director wages, growth that hasn’t shown up in last year’s tax return yet. I build the case for where your business is actually headed, and structure the loan so it helps you grow.
Prefer to talk first? Call Durand direct on 0450 275 656
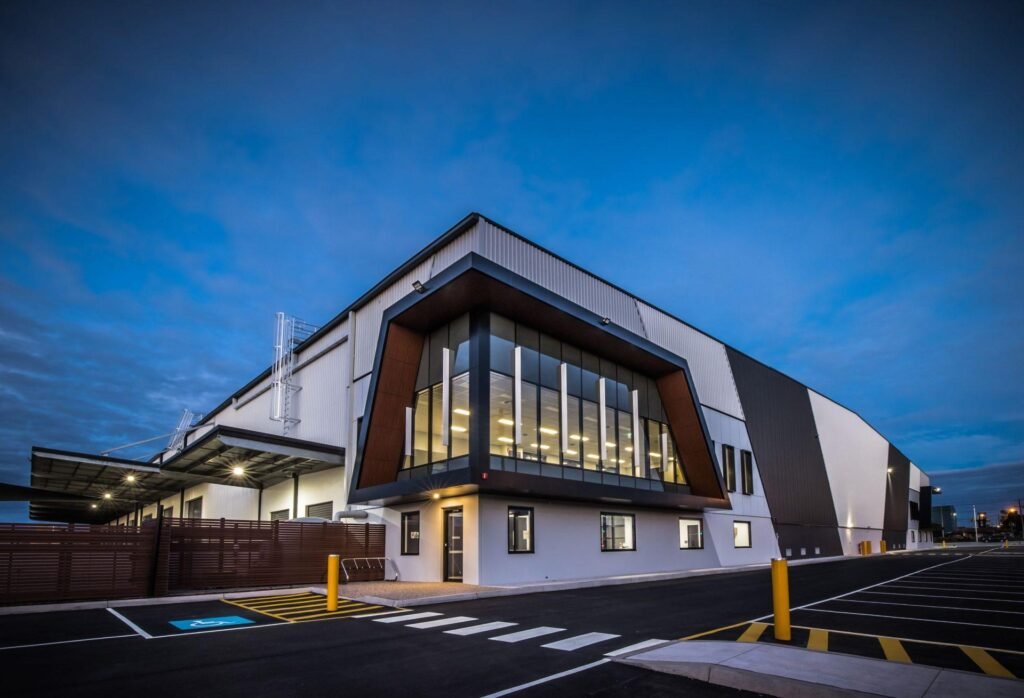
Moving a South East Melbourne law firm from renting to owning
Situation: A growing law firm that had always rented, with income spread across profits, addbacks and director wages.
Result: An off-the-plan office bought, with room to grow into.
A law firm in Melbourne’s South East that had always rented their offices came to me ready to buy: an off-the-plan commercial property that would give them room to grow into. The challenge wasn’t finding the property. It was that their income didn’t fit neatly into a lender’s standard checklist: like a lot of professional practices, it showed up across net profits, addbacks and director wages rather than one clean figure.
I worked through their financials in detail to build an accurate picture of what the business could actually service. But the real work was making the case for where the firm was headed, not just where it had been: a growing legal practice that had outgrown its current space and was going to need more room, not less. That meant workshopping the structure directly with the lender, rather than submitting a standard application and hoping it fit.
The result: a firm that had only ever rented is now settled into premises built for where their business is going next.
Sound like your situation? Tell me about your business and the property you have in mind, and I’ll show you how I’d structure it.
Not just a bigger home loan
Commercial finance covers offices, retail, industrial and mixed-use property, but it isn’t simply a home loan with a bigger deposit.
Lenders assess these deals differently: on the strength of the income behind them, the security type, and how the structure is put together, not just the property itself. That’s exactly where a lot of straightforward-looking applications get stuck.
Who it's for
- Professionals and business owners purchasing their own premises
- Investors seeking commercial income streams
- High-income earners expanding or diversifying their portfolio
- SMSFs investing in commercial assets
Common scenarios
- Purchasing your firm's own premises as your business outgrows rented space
- Structuring finance around complex income: net profits, addbacks, director wages
- Refinancing commercial debt to improve terms
- Purchasing commercial property via your SMSF
How I can help
Getting the loan approved isn’t the goal. Structuring it so it actually helps your business grow is. Here’s where I focus for every commercial property loan.
Complex income & serviceability
When your income shows up across net profits, addbacks and director wages rather than one clean number, I dig for the detail that’s often missed, sometimes the difference between a smaller loan and the funding your business actually needs.
Growth-focused lender presentations
Where the numbers alone undersell your trajectory, I put together the case for where your business is headed, not just where it’s been.
Tailored lending solutions
Whether you’re buying through a trust, company, SMSF or personally, I match you with lenders who understand your structure.
Loan structuring
Fixed vs variable, interest-only vs P&I, offset accounts, built around your priorities, not a default template.
How commercial lending with me works
Commercial finance is complex. The process working with me shouldn’t be.
Why business owners work with me
You’ll deal with me from the first conversation to settlement, working alongside your accountant and solicitor.
23+
Years in financial services
70+
Lenders on panel
5★
Google rating
1:1
End-to-end service, no handoffs
Commercial property loan FAQs
What is a commercial property loan?
A commercial property loan is finance secured against property not classified as residential, offices, retail premises, industrial assets, medical suites or mixed-use buildings. Commercial loans are typically more complex than residential lending, often involving detailed income analysis, higher deposits and more strategic structuring.
What deposit do I need for a commercial property loan?
Commercial property loans generally require a higher deposit than residential lending, often in the range of 30% or more depending on the property type, the lender and your financial position. An accurate figure depends on your specific circumstances and the asset you’re purchasing.
Can I buy commercial property through my SMSF?
Yes. Purchasing commercial property through your SMSF is a common strategy, structured through a compliant Limited Recourse Borrowing Arrangement. It’s covered in more detail on the SMSF Lending page, since it involves its own set of compliance and lender requirements.
What if my business income doesn't fit a standard lending checklist?
This is common for professional practices and growing businesses, where income shows up across net profits, addbacks and director wages rather than one clean figure a lender can read at a glance. In these cases, the loan application needs to include a clear picture of the business’s trajectory, not just its most recent tax return, often worked through directly with the lender rather than submitted as a standard application.
Ready to finance your next commercial property?
Tell me what you’re working toward and I’ll come back with the lending structure that actually fits.
Related reading
Want to go deeper before you get in touch? Start here.
7 key considerations when buying commercial property through an SMSF
What to think through before using your self-managed super fund to purchase a commercial asset.
What to consider when refinancing?
A practical look at what’s worth weighing up before refinancing an existing loan, commercial or otherwise.
Explore more lending options
Commercial property is one piece of the picture. Here’s where else to look.
Commercial lending
See the full range of commercial lending services, including how commercial and SMSF lending work together.
SMSF lending
Buying commercial or residential property through your super fund? See how SMSF lending is structured.
Residential lending
Looking for a home loan, refinance or investment property loan instead? Explore residential lending services.