Debt recycling strategy
Your mortgage can do more than sit there. It can build your wealth.
Turning non-deductible home loan debt into tax-deductible investment debt sounds simple on paper. My focus is making sure the structure actually converts your debt into wealth, without overstretching you.
Prefer to talk first? Call Durand direct on 0450 275 656
Turning peak earning years into a head start on financial freedom
Situation: A professional couple with three children and a $547,000 home loan, in their peak earning years.
Result: A clean $100,000 investment split, with the income directed back into their home loan.
A professional couple in their early 40s, with three children and private school fees for their eldest, were two years into their highest-earning years on a combined income of around $250,000. They didn’t want to just keep chipping away at the mortgage. They wanted to use this stage of life to build a genuine nest egg.
Their home was valued at just over $1.015 million with a $547,000 loan. Working with their financial adviser and accountant, I split $100,000 of equity into its own investment loan, kept completely separate from a further $30,000 drawn for renovations and added to the home loan. That separation is what keeps the investment interest deductible and the structure audit-ready.
With their planner, they invested $50,000 straight away into a portfolio of ETFs and drip-fed the other $50,000 into the market over the following months to manage timing risk.
The client has advised that the $100,000 is now fully invested, generating income of approximately 4% annually, which is being directed straight back into paying down their non-deductible home loan debt, while school fees and everyday life continues to be covered comfortably from their PAYG earnings cash flow.
The strategy gives this professional couple two things at once: a faster path to clearing non-deductible debt during their peak earning years, and the flexibility to sell the investment and be completely debt-free whenever they choose.
Sound like your situation? Tell me about your home loan and your goals and I’ll give you an honest read on whether debt recycling fits.
Not just a repayment strategy
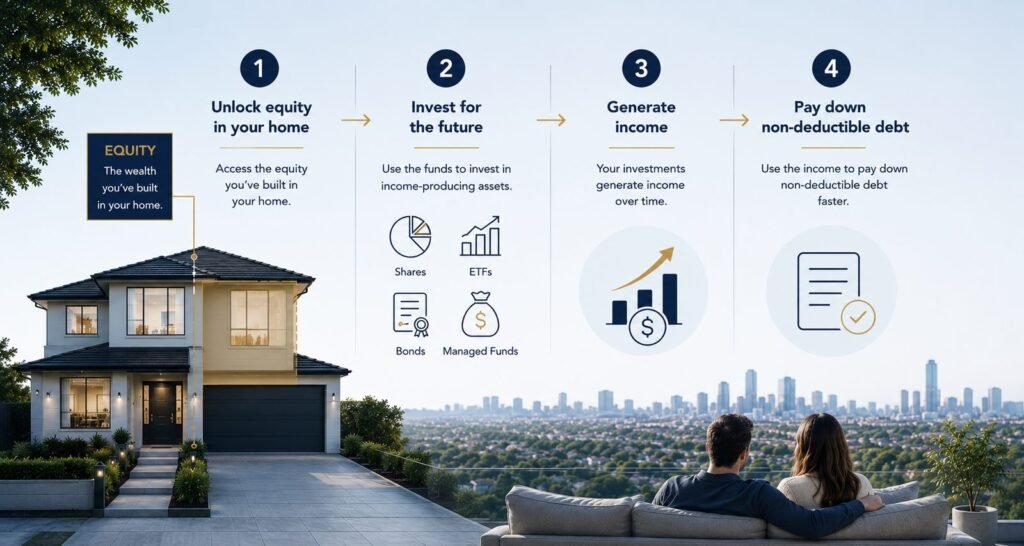
Debt recycling isn’t just making extra repayments with a different label. It involves using available equity or surplus repayments to invest in income-generating assets, reborrowing that amount through a loan split kept clearly separate from your home loan, and directing the investment returns and tax benefits back into accelerating repayment and further investment. The mechanics are simple to describe, but you need a good mortgage broker, a good financial planner and good accountant all working together for your best interest. Getting the structure right for your serviceability, tax position, and risk tolerance is where most of the value, and most of the risk, sits.
It's a strategy best suited to
- Stable, high household incomes
- Owner-occupied home loans with genuine, useable equity
- Strong cash flow and capacity for surplus repayments
- A long-term investment mindset, not a quick win
- A tolerance for some investment risk
Why clients choose me for debt recycling
I don’t just arrange the loan split, I look for the detail in your numbers that makes the difference between a structure that merely works on paper, and one that actually builds wealth.
How I can help
Getting a loan split arranged isn’t the goal. Structuring it so it genuinely builds wealth is. Here’s where I focus for every debt recycling strategy.
Structure that holds up to scrutiny
Clean loan splits and correctly traced funds, documented in a way that satisfies your accountant and, if it ever comes to it, the ATO.
Serviceability built for the long game
I model your borrowing capacity against real buffers, not just today’s rate, so the strategy can survive a rate rise or a quieter income year.
Coordination with your adviser & accountant
I structure the lending. Your adviser picks the investments and your accountant confirms the tax treatment. I make sure all three plans line up.
Cash flow & risk review
An honest look at whether your income and buffer can sustainably support the investment loan, not just whether a lender will approve it.
How debt recycling with me works
Debt recycling is complex. The process working with me shouldn’t be.
Why professionals work with me
You’ll deal with me every step of the way, working alongside your accountant so the structure stays on track.
23+
Years in financial services
70+
Lenders on panel
5★
Google rating
1:1
End-to-end service, no handoffs
Debt recycling FAQs
What is debt recycling in simple terms?
Debt recycling is a strategy that gradually turns your non-deductible home loan debt into tax-deductible investment debt. Instead of just paying down your mortgage, you use your growing equity or surplus repayments to invest in income-producing assets, and the loan used for that investment can generate a tax deduction on its interest.
How much equity do I need to start debt recycling?
There is no fixed minimum, but most lenders and brokers look for a loan-to-value ratio comfortably below 80 percent so there is genuine, useable equity once buffers and serviceability are accounted for. The right starting point depends on your property value, your existing loan balance, and how much surplus cash flow you have to support the investment loan.
Is debt recycling risky?
Debt recycling increases your overall borrowing and links that borrowing to investment markets, so it carries more risk than simply paying down your mortgage. Property and share markets can fall, interest rates can rise, and the strategy works best when you have stable income, a cash flow buffer, and a long-term outlook. It is not suitable for everyone, which is why the structure needs to be assessed against your personal circumstances.
Do I need a financial adviser as well as a mortgage broker for debt recycling?
In most cases, yes. As your mortgage broker, I structure the lending side of the strategy, including loan splits and how funds are drawn and invested. Investment selection and tax advice sit with a financial adviser and accountant, and the strongest debt recycling strategies are built with all three working from the same plan.
Ready to explore debt recycling?
Tell me about your home loan and your goals and I’ll come back with an honest read on whether debt recycling fits your numbers.
Related reading
Want to go deeper before you get in touch? Start here.
Debt recycling: a case study
How another couple used debt recycling to turn their mortgage into a wealth-building engine.
Offset vs Redraw
Not ready for debt recycling yet? Here’s how to make the most of your home loan in the meantime.
Explore more lending options
Debt recycling is one piece of the picture, here’s where else to look.
Equity release
Unlock the equity in your home for other wealth-building goals, whether or not debt recycling is the right fit.
Investment property loans
Prefer property over shares or managed funds? See how investment property lending is structured for growth.
SMSF lending
Looking to build wealth through your super instead of, or alongside, your home loan? Explore SMSF lending.