Lending that understands life on the Peninsula
From the vineyards of Red Hill to the back beach at Sorrento, we structure home, holiday-home, acreage and SMSF lending for people building a life — or a legacy property — across the Mornington Peninsula.
Not every Peninsula purchase looks the same
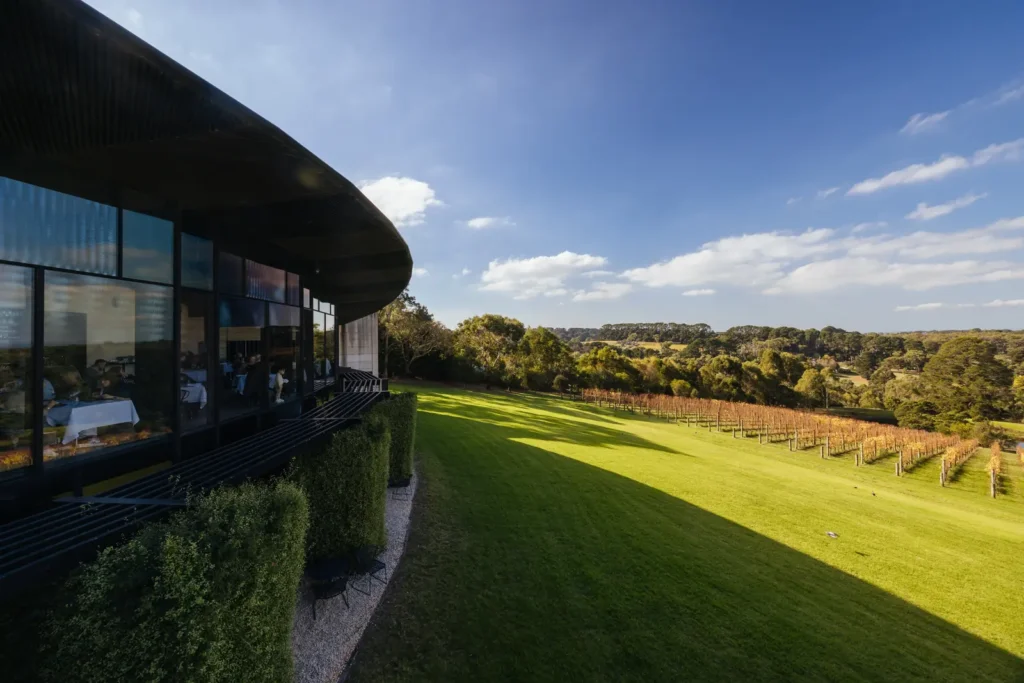
The Mornington Peninsula covers a lot of ground, and every part of it borrows differently. Mornington and Mount Eliza are increasingly full-time family suburbs, close enough to the freeway for a commute. Mount Martha and Balnarring sit somewhere between lifestyle and full-time living, often with larger blocks and a slower pace. Red Hill and Flinders are where hobby farms, vineyards and equestrian properties come into play, while Sorrento and Portsea remain the Peninsula’s premium holiday-home and legacy-property market.
We work all of it — which is why we don’t default to a standard residential loan when a client actually needs acreage lending, a construction facility for a coastal build, or a holiday-home structure that keeps their main residence loan untouched.
The Mornington Peninsula by the numbers
A snapshot of who lives here, how the population is changing, and what property is doing across the Peninsula right now.
173,022
Mornington Peninsula Shire population, 2024
65-74
Largest resident age bracket
0.30%
Average annual population growth to 2036
$1.4M–$5.5M
Typical house price range across the 8 suburbs
Household & age profile
- The Shire's population skews older than most of Melbourne, with the biggest growth forecast in the 75–79 age bracket over the next few years
- Mornington, Mount Eliza and Mount Martha remain the three largest, most family-oriented townships on the Peninsula, with the strongest year-round (non-holiday) demand
- Sorrento and Portsea skew heavily toward holiday and weekender ownership, which shapes how lenders assess those purchases
Where the growth is
- Population growth Shire-wide is slow and steady — this is a mature, largely built-out region, not a growth corridor
- Mount Eliza recorded the strongest house price growth of the group over the past year, a sign of sustained demand from Melbourne relocators
- Bittern and Crib Point, on the Western Port side, have shown the fastest price growth Shire-wide, though from a lower base and on thin sales volumes
| Suburb | Typical house price |
|---|---|
|
Flinders |
~$5.5M |
|
Portsea |
~$4.1M |
|
Red Hill |
~$1.9M |
|
Sorrento |
~$1.9M |
|
Mount Eliza |
~$1.9M |
|
Balnarring |
~$1.9M |
|
Mount Martha |
~$1.7M |
|
Mornington |
~$1.4M |
Data current as of August 2026. Source: CoreLogic property data via Picki suburb reports. Property prices change regularly, and Peninsula figures are especially sensitive to a small number of high-value sales in suburbs like Flinders and Portsea — figures shown here are indicative and should be confirmed against current listings before relying on them.
Land size varies more here than almost anywhere else we cover — a Sorrento or Portsea block often sits under 700m², while lifestyle and hobby-farm properties around Red Hill and Flinders commonly run from one to several acres, which is exactly why acreage lending needs its own approach.
Average home loan sizes
Victoria’s average new owner-occupier home loan sits at $675,000 (ABS Lending Indicators, March 2026 quarter). Across the Peninsula’s three largest, most family-oriented townships — Mornington, Mount Eliza and Mount Martha — typical loan sizes run well above that benchmark.
| Suburb | Typical house price | Estimated average home loan* |
|---|---|---|
|
Mornington (largest township) |
~$1.4M |
~$980,000 |
|
Mount Eliza |
~$1.9M |
~$1.33M |
|
Mount Martha |
~$1.7M |
~$1.19M |
|
Peninsula-wide average (8 suburbs) |
~$2.54M
|
~$1.78M |
*Estimated using each suburb’s typical house price and a 70% loan-to-value ratio (30% deposit or equity). The Peninsula-wide figure is skewed upward by a small number of ultra-premium sales in Flinders and Portsea, so it’s a less reliable guide than the individual township figures above. This is illustrative only — actual loan size depends on your deposit, existing equity and borrowing capacity. Get a personal borrowing power assessment for an exact figure.
Well-regarded local schools
- Peninsula Grammar & Toorak College, Mount Eliza (independent)
- Padua College, Mornington/Rosebud/Tyabb & Balcombe Grammar, Mount Martha (independent)
- Mornington Secondary College & Mount Eliza Secondary College (state)
Landmarks locals love
- Sorrento back beach & Point Nepean National Park
- Arthurs Seat summit and eagle chairlift
- Red Hill wineries and the Red Hill Community Market
- Flinders blowhole, ocean beach and golf links
Sources: Mornington Peninsula Shire population and forecast data, profile.id / forecast.id (2023–2024); ABS Census of Population and Housing 2021; CoreLogic and Picki suburb data (2026); ABS Lending Indicators, March quarter 2026 (Victoria average loan size). Figures are indicative and change regularly — ask us for the latest data on a specific suburb.
Lending structures built for the Peninsula
Lifestyle & Acreage Lending
Hobby farms, equestrian blocks and vineyard-adjacent properties around Red Hill, Flinders and Balnarring need a lender comfortable with land size, zoning and any income-producing use. We structure these on a case-by-case basis, not a standard residential template.Holiday Home & Second Property Finance
A Sorrento or Portsea holiday home is rarely funded the same way as a primary residence. We look at whether it makes more sense as an additional owner-occupied loan, an investment structure, or a facility drawn against equity in your main home.Bridging Finance for Sea Changers
Moving to Mount Eliza or Mount Martha often means timing the sale of one property against the purchase of another. Bridging finance keeps you from having to sell before you’ve secured the right home.A recent Peninsula scenario
Buying in Mount Martha before their Melbourne home sold
A family relocating to Mount Martha found the right home before their own had sold, with only a fortnight to make an unconditional offer. We structured a bridging loan using both properties as combined security, so the bank assessed their “end debt” — what they’d owe once the Melbourne sale settled — rather than the higher “peak debt” of briefly holding two mortgages. Interest simply accrued during the overlap instead of requiring repayments on both loans at once, so they weren’t pushed into a rushed, discounted sale. Once Melbourne sold, the proceeds cleared the bridge in full, leaving them with one simple mortgage on Mount Martha.
Mornington Peninsula home loan FAQs
Can I get finance for a lifestyle acreage property in Red Hill or Balnarring?
Yes, though lenders assess acreage and hobby-farm properties differently to standard residential purchases, particularly around land size, zoning and any income-producing use such as a vineyard or agistment. We work with lenders who understand Red Hill and Balnarring lifestyle blocks and structure the loan around the actual use of the land.
Is a holiday home in Sorrento or Portsea harder to finance than a primary residence?
Holiday and second homes are generally financed similarly to an investment or additional owner-occupied purchase, but deposit and serviceability requirements can differ from lender to lender. It comes down to how the property will be used and how your existing mortgage and income are structured.
What lending structure suits a sea change or tree change move to the Peninsula?
Many clients moving to Mount Eliza or Mount Martha need to bridge the sale of their existing home with the purchase of their new one. Bridging finance, or a well-timed settlement structure, can prevent you from having to sell before you’ve secured the right property.
Can I use my SMSF to buy a rural or lifestyle property on the Peninsula?
It’s possible, but it comes with stricter criteria than a standard residential SMSF purchase, particularly if the land has any commercial or agricultural use. A proper assessment of your fund and the specific property is essential before you commit.
Planning a move to the Peninsula?
Whether it’s a lifestyle block, a holiday home or a full sea change, tell us what you’re working toward and we’ll map out the lending structure to match.