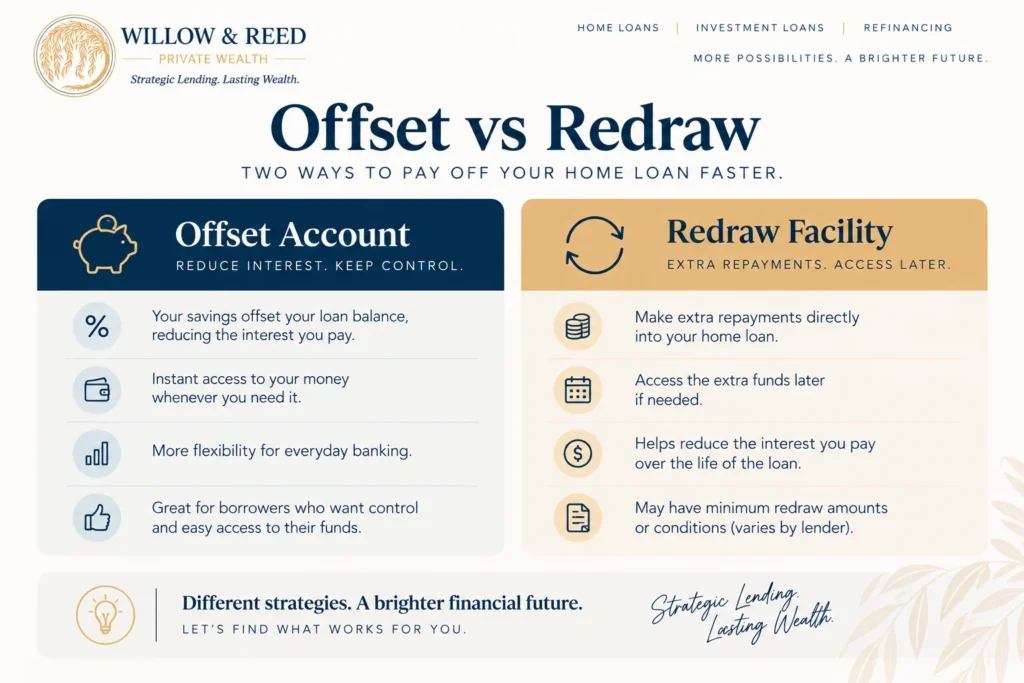
An offset account and a redraw facility can both cut the interest on your mortgage and shorten your loan term. The real difference is how you get to your money along the way, not how much you can save in theory.
If you want instant, unlimited access to your extra savings, an offset account is usually the better fit. If you would rather build in a small barrier before you can touch that money again, a redraw facility can do a similar job.
How an offset account works
An offset account works much like an everyday bank account that sits alongside your home loan. You can deposit and withdraw money whenever you like, and many lenders will even give you a debit card linked to the account.
The difference is what that balance does for you. Instead of earning interest like a savings account, the money in your offset account reduces the loan balance your lender charges interest on. The more you keep in there, the less interest you pay overall.
Because interest is calculated daily on most home loans, an offset account rewards you the moment your income lands. Having your salary paid straight into your offset account, rather than a separate everyday account, is one of the simplest ways to get the most out of it.
How a redraw facility works
A redraw facility works differently. Rather than sitting in a separate account, any extra repayments you make go straight onto your loan, reducing the principal directly.
Because that extra amount is not part of your regular principal and interest repayment, it goes entirely towards paying down your loan, rather than being split between principal and interest. Over time this can meaningfully shorten your loan term.
You can usually still access those extra repayments if you need to, but most lenders attach some kind of friction to it, such as a withdrawal fee, a minimum withdrawal amount, or a cap on how often you can redraw in a given period.
A simple example of the savings
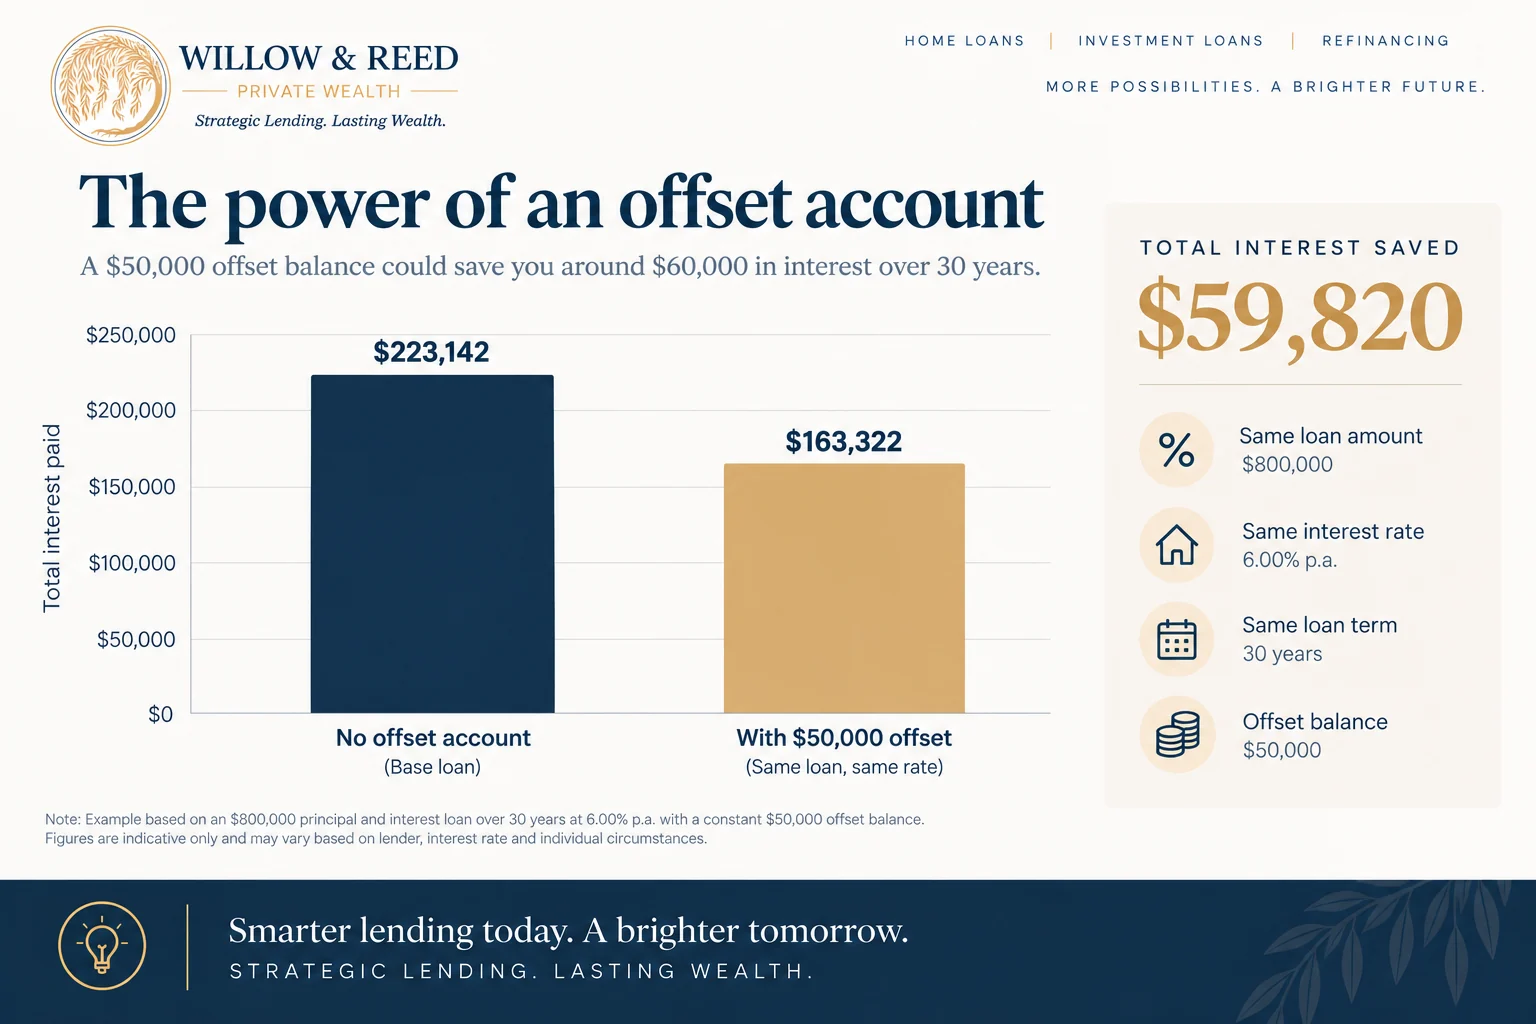
Here is a simple, generic example to show the mechanics. This is an illustration only, not a real client’s figures. Say you have $20,000 sitting in a high interest savings account earning 1.5% p.a., separate from a $450,000 home loan charged at 2.9% p.a.
- In the savings account, that $20,000 earns you around $300 a year, or roughly $25 a month.
- In an offset account attached to the same loan, that $20,000 reduces the balance interest is calculated on to $430,000. On these numbers, your monthly repayment could drop from around $1,088 to around $1,040, a saving of about $48 a month.
That is roughly $23 a month more than the savings account was earning you, simply because the offset account is doing two jobs at once, keeping your cash accessible and reducing your interest bill.
A redraw facility can achieve a similar result if that same $20,000 is paid directly onto the loan as an extra repayment instead. The main trade off is how easily you can get that money back out again.
Offset vs redraw: which one suits you
In my experience, the right choice comes down to your own habits with money more than anything else.
- Choose an offset account if you are disciplined with your spending and want your savings working for you without being locked away. You get full flexibility, and the temptation to dip into it for a big purchase is a personal risk, not a structural one.
- Choose a redraw facility if you know you are tempted to spend surplus cash, and a small amount of friction, such as a fee, a minimum withdrawal, or a limit on how often you can access funds, will help you leave the money where it is doing the most good.
Both options give you the same broad outcome, less interest paid, and the potential to pay off your home loan sooner. Which one is better really depends on which one you will actually stick to.
Tax considerations if you have an investment loan
If you have an investment property loan, the choice between offset and redraw can also affect your tax position. Withdrawing funds from a redraw facility can make it harder to claim the interest on that portion as a tax deduction, unless you can clearly show the funds were used for further investment purposes.
An offset account tends to be cleaner from a tax perspective, because the loan balance itself is not reduced by a contribution, so your full loan amount generally remains deductible where the loan was used for investment purposes.
This is general information only. I am not a tax adviser, so please speak with your accountant or financial adviser before making decisions based on your own tax position.
Frequently asked questions
What is the main difference between an offset account and a redraw facility?
An offset account is a separate transaction account linked to your home loan. The balance reduces the amount your lender charges interest on, without being a contribution to the loan itself. A redraw facility works differently. Extra repayments go straight onto the loan balance, and you can access them later, subject to your lender’s conditions.
Which saves more interest, an offset account or a redraw facility?
Used well, both can save a similar amount of interest, because both reduce the balance your interest is calculated on in real terms. The bigger factor is usually how consistently you use the account and how much you are able to keep in it, rather than which structure you choose.
Can I access my money in an offset account as easily as a normal bank account?
Yes. Most offset accounts work like an everyday transaction account, including day to day access and sometimes a linked debit card. That flexibility is the main appeal for disciplined savers.
Does a redraw facility cost anything to use?
It depends on the lender. Some charge a fee per withdrawal, set a minimum redraw amount, or limit how many times you can access funds in a given period. These conditions can actually help less disciplined savers by making it a bit harder to dip into extra repayments.
Will using a redraw facility affect my tax deductions on an investment loan?
It can. If you redraw funds from an investment loan for a personal purpose, you may not be able to claim the interest on that portion as a tax deduction. Speak with your accountant before making decisions based on your own tax position, since this varies case by case.