The fastest way to pay off your mortgage sooner is a combination of small, consistent moves, more frequent repayments, extra contributions when you can, and keeping your interest rate competitive, rather than one single trick.
Below are 11 practical strategies I regularly discuss with clients. You do not need to use all of them at once. Even adopting two or three consistently can shave years off your loan and save you a meaningful amount in interest.
1. Switch to fortnightly repayments instead of monthly
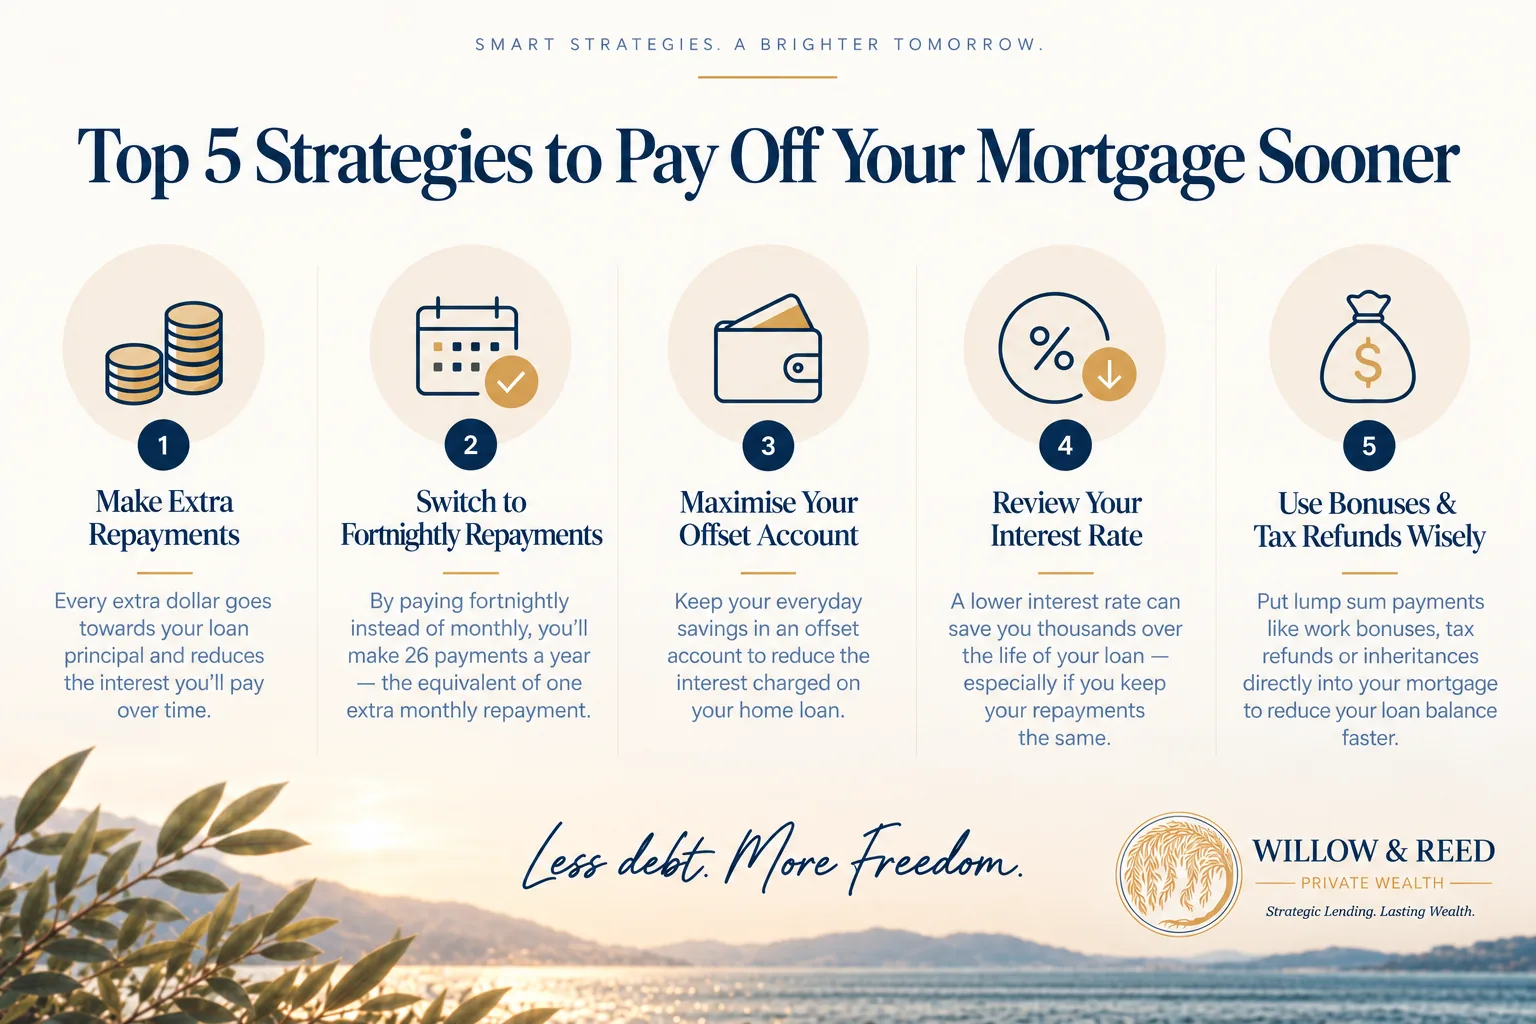
Simply changing your repayment frequency from monthly to fortnightly can make a real difference. Because there are 26 fortnights in a year rather than 12 months, paying half your monthly amount every fortnight works out to the equivalent of 13 monthly repayments a year instead of 12.
That extra repayment goes straight towards your loan, and because it happens automatically once you set it up, there is no ongoing willpower required.
2. Make extra repayments whenever you can
Extra repayments, even irregular ones, go a long way over the life of a loan. As a simple, generic illustration, on a $500,000 loan over 25 years, contributing an extra $500 a month could reduce the loan term by around 5 years and save in the order of $50,000 in interest. These figures will vary depending on your rate and loan structure, and are not a specific client’s outcome.
Tax time refunds, bonuses and one off windfalls are all good candidates for a lump sum extra repayment, provided your loan allows it without a penalty.
3. Shop around for a lower interest rate
Loyalty rarely gets rewarded in home lending. It is worth comparing your current rate and features against what else is available at least once a year.
If you find a better deal elsewhere, it is also worth giving your current lender the chance to match it before you go to the trouble of switching. Just make sure you weigh up any exit or establishment fees against the savings on offer.
4. Keep your repayments the same after refinancing to a lower rate
When you refinance to a lower rate, it is tempting to reduce your monthly repayment and enjoy the extra cash flow. If your goal is to pay the loan off sooner, keeping your repayment at the old, higher level instead means the difference goes straight towards your principal.
You will not notice the change in your day to day budget, because you were already used to paying that amount, but your loan balance will fall faster.
5. Make the most of an offset account
An offset account, typically available on variable rate loans, reduces the balance your interest is calculated on by the amount you hold in it. Directing your salary and everyday spending money through your offset account, rather than a separate transaction account, maximises the benefit.
For a full breakdown of how offset accounts compare to a redraw facility, see my article on offset vs redraw.
6. Avoid interest only terms where you can
Interest only loans usually carry a higher interest rate than principal and interest loans, and none of your repayment reduces the amount you owe. For an owner occupied home you are planning to pay off, principal and interest repayments are generally the better structure.
Interest only terms have their place for some investment strategies, but they should be a deliberate choice, not a default.
7. Direct all your income into your offset account
Because interest on most home loans is calculated daily, having your salary and other income land in your offset account, even briefly before it is spent, reduces the interest charged that day. Over a year, this habit alone can save you hundreds of dollars.
8. Focus extra repayments on the early years of your loan
In the early years of any home loan, the bulk of your regular repayment goes towards interest rather than principal. This means extra repayments made early in the life of your loan have an outsized effect on your total interest bill and loan term, compared with the same extra repayment made later on.
If you can front load extra contributions in the first five to ten years, you will feel the benefit for the rest of the loan.
9. Consider consolidating higher interest debts
If you are carrying credit card debt, a personal loan, or a car loan alongside your mortgage, consolidating that debt into your home loan can reduce the total interest you are paying, since mortgage rates are typically well below credit card and personal loan rates.
This only works in your favour if it is paired with genuine budgeting discipline. Consolidating debt without addressing the spending that created it, and without closing the credit facility you consolidated, tends to see the debt creep back.
10. Redirect a few everyday luxuries towards your mortgage
Small, regular spending adds up faster than most people expect. As a simple illustration, two takeaway coffees a day at around $4 each is roughly $8 a day, $40 a week, and around $2,080 a year. Add a handful of streaming subscriptions at say $50 a month, and that is another $600 a year.
You do not need to cut everything out. Redirecting even a portion of discretionary spending towards extra mortgage repayments can meaningfully speed up your payoff timeline.
11. Ask about professional package loans if you qualify
Some lenders offer discounted loan packages for certain professions, including doctors, lawyers and accountants, and for members of some professional associations. These packages can include a reduced interest rate, and in some cases a waived or reduced Lenders Mortgage Insurance premium.
If you fall into one of these categories, it is worth asking whether you qualify. If you are a medical professional specifically, I have written more about the lending options available to you in why medical professionals should use a mortgage broker.
Frequently asked questions
Will paying fortnightly instead of monthly really make a difference to my mortgage?
Yes. Because there are 26 fortnights in a year, paying half your monthly repayment every fortnight adds up to the equivalent of 13 monthly repayments instead of 12, without you having to find any extra money.
How much can extra repayments actually save me?
It depends on your loan size, rate, and how much extra you contribute. As a general illustration, an extra $500 a month on a $500,000 loan over 25 years could reduce the term by around 5 years and save roughly $50,000 in interest. Your own numbers will differ, so it is worth running your actual figures.
Should I avoid interest only loans altogether?
Not necessarily, but for an owner occupied home loan you are trying to pay off sooner, principal and interest repayments are generally the better default, since interest only terms usually carry a higher rate and do not reduce what you owe.
Is consolidating my other debts into my mortgage a good idea?
It can reduce your overall interest cost, since mortgage rates are typically lower than credit card or personal loan rates. It only works well if you also address the spending habits that created the debt, and close the facilities you consolidate.
Do professional package loans really offer better rates?
Many lenders offer discounted packages to certain professions such as doctors, lawyers and accountants, which can include a lower interest rate and reduced or waived Lenders Mortgage Insurance. Eligibility and the exact benefit vary by lender, so it is worth checking your options.