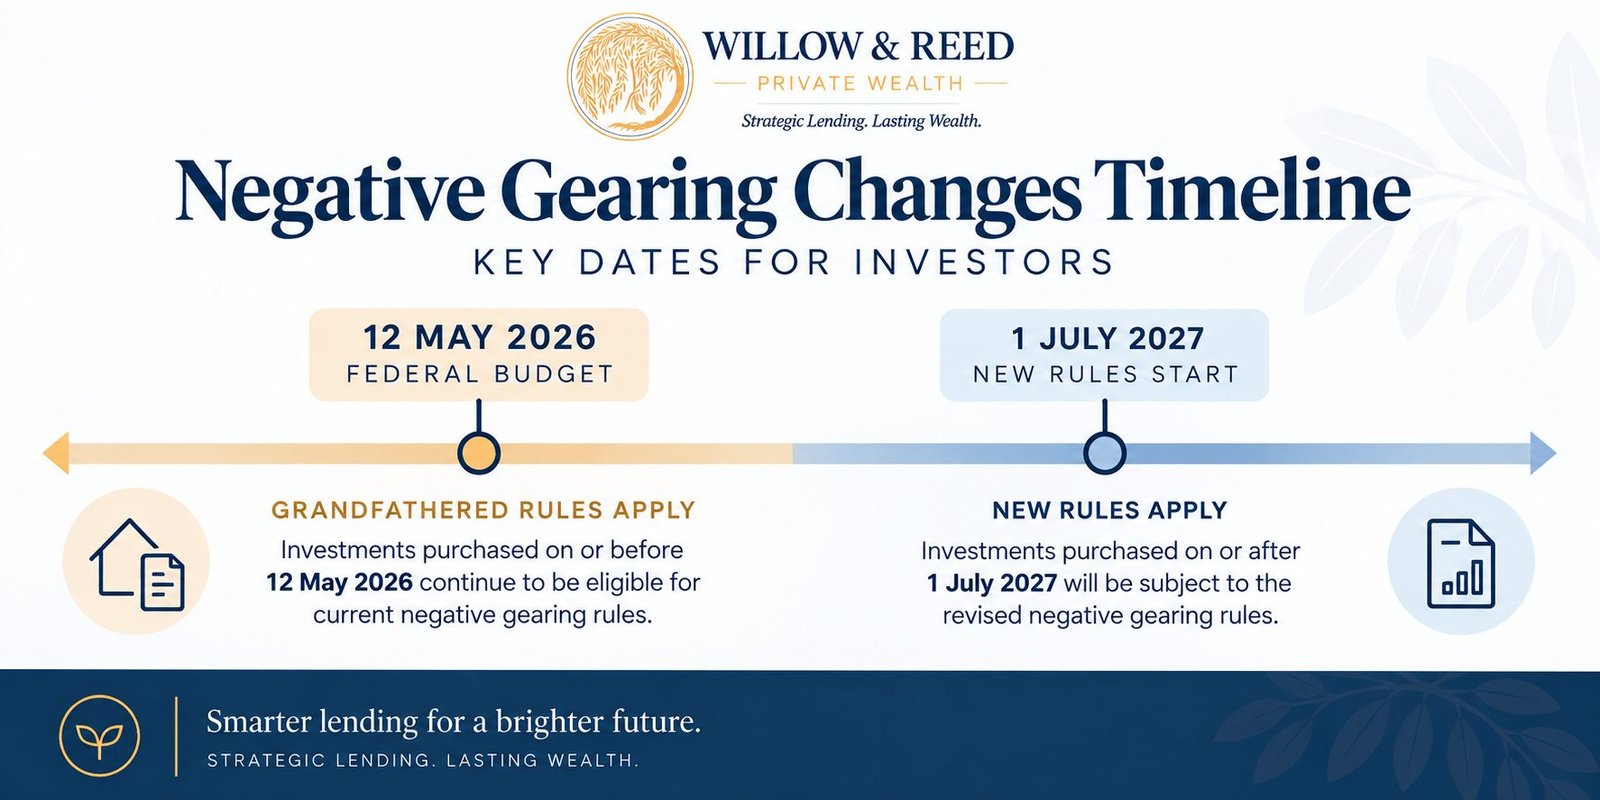
From 1 July 2027, negative gearing on residential property will be limited to new builds, and established properties bought after budget night can still have their losses offset against rental income, but not against your salary or other income. If you already owned an investment property before 7:30pm AEST on 12 May 2026, none of this changes for you, your existing arrangement is grandfathered under the old rules.
This isn’t a client case study, it’s the plain-English explainer I’ve been giving clients since the reform was announced, because the headlines have caused more confusion than clarity.
What’s actually changing, in plain terms
Negative gearing lets an investor offset a property’s losses, when the rent doesn’t cover the mortgage and other costs, against their other income, reducing their overall tax bill. Under the reform, that full offset against other income will only be available for negatively geared new builds. For an established (existing) property bought after budget night, losses can still be claimed against the rental income that property generates, and any unused loss can be carried forward, but it can no longer be used to reduce tax on your salary or other earnings.
Alongside this, the 50% capital gains tax discount is being replaced with cost base indexation and a 30% minimum tax rate on capital gains, applying to gains that accrue after 1 July 2027. New build investors will retain a choice between the old 50% discount and the new arrangement, an added incentive built into the reform.
Who’s grandfathered, and who isn’t
The date that matters is 7:30pm AEST, 12 May 2026, when the reform was announced.
- Held before budget night: Your property keeps its existing negative gearing and CGT treatment indefinitely, nothing changes unless you sell and rebuy.
- Established property bought after budget night: From 1 July 2027, losses are quarantined to that property’s rental income rather than offsetting your broader income, with unused losses carried forward.
- New build purchased at any time: Retains full negative gearing against other income, this is the deliberate carve-out designed to keep investment flowing into new housing supply.
The practical effect is that the property you already own is unaffected, but the type of property you buy next genuinely matters in a way it didn’t before.
Why this reform exists, and what it’s trying to do
The stated goal is to redirect investor demand toward new housing supply rather than competition for existing stock, while protecting people who’ve already structured their finances around current rules. Whatever view you take on the policy debate, the mechanics are what matter for your own planning.
- Limiting full negative gearing to new builds is meant to encourage construction, since an investor loses less tax benefit by building or buying new than by buying established.
- Grandfathering existing holdings avoids retrospectively changing the deal for people who already own investment property, which is why nothing changes for pre-budget-night purchases.
- The CGT change, cost base indexation plus a 30% minimum rate, is designed to work alongside the negative gearing change rather than as a separate, unrelated measure.
Understanding the intent helps make sense of why the rules land differently depending on exactly what and when you buy.
What this means for your next move
If you’re planning to add to an investment portfolio, the calculus has genuinely shifted, and it’s worth thinking through deliberately rather than reactively.
- A new build purchased after 1 July 2027 keeps the full negative gearing benefit against your other income, which changes the relative attractiveness of new construction, off-the-plan, and house-and-land packages compared to buying established.
- An established property bought after budget night can still make sense, particularly if the rental yield is strong enough that quarantined losses aren’t the main driver of the investment case.
- If you’re close to exchanging on an established property, understanding exactly where budget night and the 1 July 2027 start date sit relative to your settlement matters for how the property will be treated.
None of this changes the fundamentals of good property selection, location, growth potential, tenant demand, but it does change the tax mechanics sitting underneath the decision.
Is this right for you?
If you already hold investment property bought before budget night, there’s genuinely nothing to do differently, your position is protected as is.
If you’re planning your next purchase, this is worth factoring into the conversation early, alongside your accountant, since the right structure now depends on new build versus established in a way it simply didn’t a year ago.
If you’re weighing up how a new build purchase actually gets financed and structured, it’s worth reading loan splitting strategy alongside this one.
Frequently asked questions
When do the new negative gearing rules actually start?
The changes apply from 1 July 2027. Properties held before 7:30pm AEST on 12 May 2026, when the reform was announced, are grandfathered and unaffected. What matters for a new purchase is whether it’s an established property or a new build, and when it settles relative to these dates.
Does this mean I can never negative gear an established property again?
No. An established property bought after budget night can still have its losses offset against the rental income that property earns, and unused losses carry forward. What changes is that those losses can no longer be used to reduce tax on your salary or other income, which is the part that’s genuinely different from current rules.
Is my current investment property affected?
If you held it before 7:30pm AEST on 12 May 2026, no. It keeps its existing negative gearing and capital gains tax treatment under the grandfathering provisions, regardless of what you do next with other properties.
Should I talk to my accountant about this before buying again?
Yes, definitely. This is general information about how the reform works, not personal tax advice, and the right approach depends on your specific financial position and goals. I’d always recommend confirming the detail with your accountant before you commit to a purchase, and I’m glad to work alongside them on the lending and structuring side.