Cross-collateralisation is when a lender uses more than one of your properties as security for one or more loans, effectively linking them together as a single pool of collateral. It’s one of the most common ways professionals with growing portfolios end up structured, usually without ever deciding to be, and it can quietly limit your options for years.
This isn’t a client case study. It’s the structuring conversation I have most often with professionals who already own two or more properties and are starting to feel boxed in when they try to refinance, sell, or borrow again.
What cross-collateralisation actually means
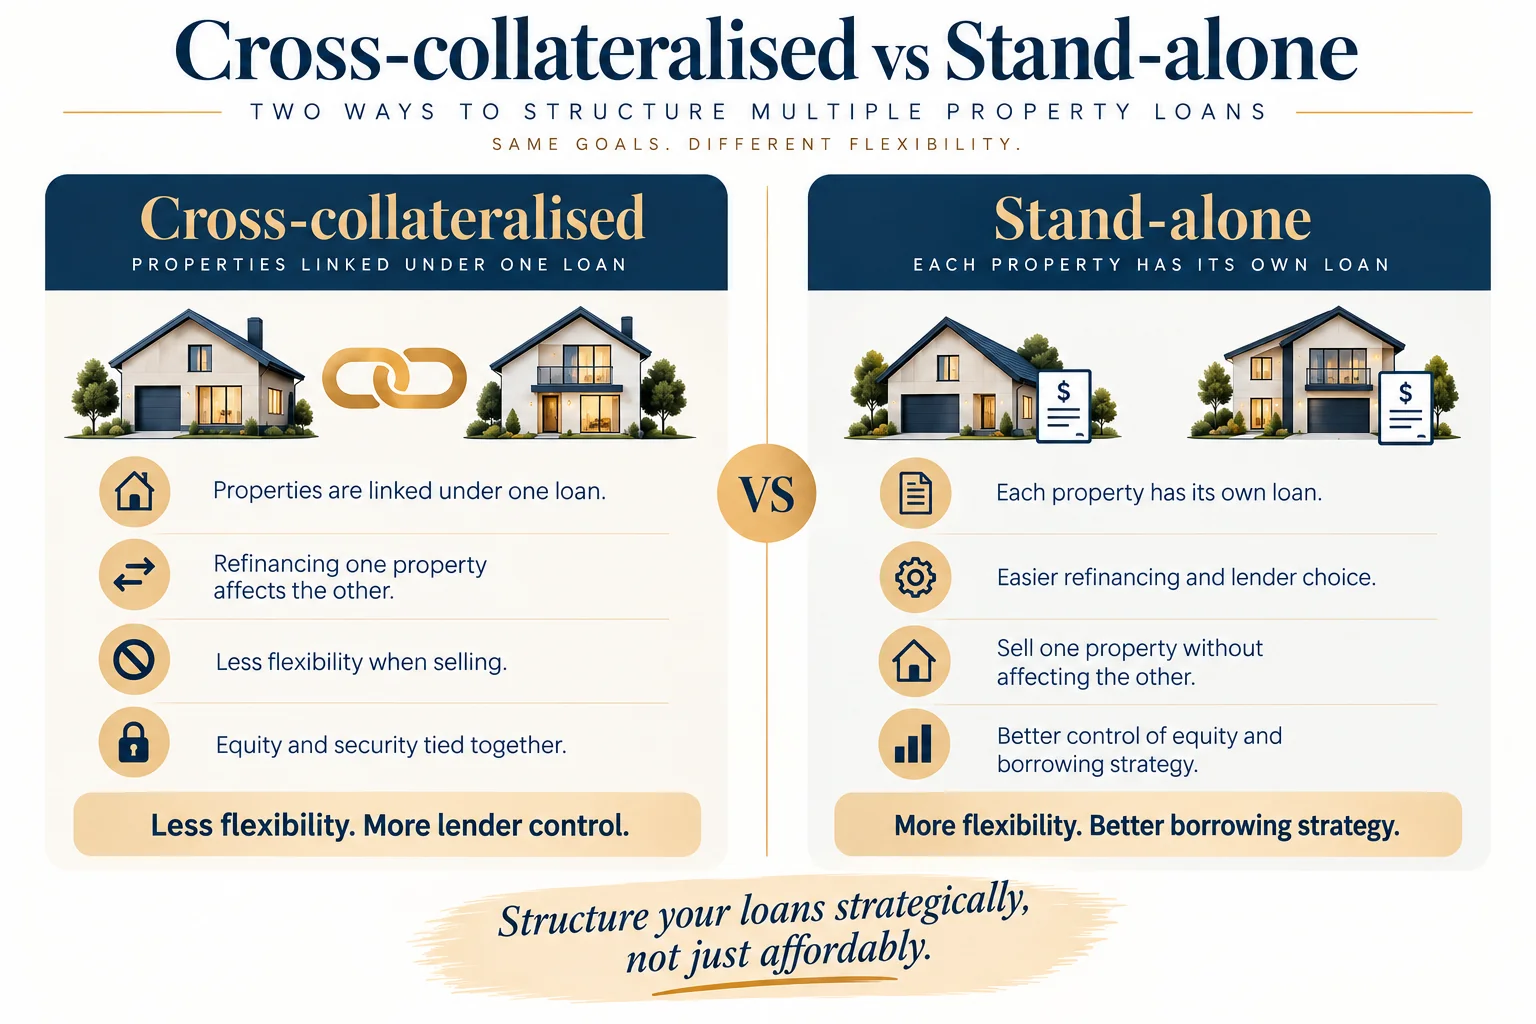
When you buy a second property using equity from your first, the bank will often ask to secure the new loan against both properties rather than just the new one. On paper it looks simple, one application, one lender, one relationship to manage. In practice, it means neither property is fully “yours” to deal with independently. The bank has a claim over both, for both loans, until everything is refinanced or repaid.
Most people don’t choose this deliberately. It’s the path of least resistance the first time a lender offers to “make it easy” and use existing equity as security instead of a cash deposit. The cost of that convenience usually shows up years later, at exactly the point you want flexibility.
Why lenders like it, and why that’s not the same as what’s good for you
Cross-collateralised lending suits the bank more than it suits you, and it’s worth understanding why before you sign anything.
- It locks in the relationship. With both properties tied to the one lender, refinancing even one loan away means untangling the whole structure, which most people avoid simply because it’s a hassle.
- It reduces the bank’s risk, not yours. If one property underperforms or a loan falls behind, the bank has recourse to the equity in your other property as well, spreading their risk across your entire portfolio.
- It limits your negotiating position. Because unwinding the structure is genuinely complicated, you lose leverage to ask for a better rate, a different lender, or a faster settlement when it matters.
None of this makes cross-collateralisation dishonest or predatory, it’s simply structured in the bank’s favour by default. The problem is that most borrowers don’t find out until they try to sell one property and discover the loan on the other is entangled in the same security agreement.
The results when you unwind it: what stand-alone lending changes
Moving to stand-alone securities, where each property secures only its own loan, changes more than most people expect.
- Selling one property no longer requires the bank to revalue and reapprove the loan on the property you’re keeping.
- You can refinance a single property to a different lender for a better rate, without touching the rest of your portfolio.
- Each loan can be structured on its own terms, interest-only where it suits your cash flow, principal and interest where it doesn’t, fixed or variable independently.
For clients with three or four properties, I’ve seen this restructure alone open up meaningful borrowing capacity simply because the lender assessing a new application can see clean, separate security rather than a tangled cross-secured mess.
Is cross-collateralisation ever the right call?
It’s not always wrong. There are situations where it’s a genuine, considered choice rather than an accident.
- Early in a portfolio, when you have limited cash for deposits and using existing equity as security is the only way to buy the next property at all.
- When you’re deliberately staying with one lender for a specific policy or servicing advantage that outweighs the flexibility cost.
- When your portfolio is genuinely finished growing and you have no plans to sell, refinance, or add properties in the foreseeable future.
Even then, I’d want it to be a decision you made with full information, not a default you fell into because it was the easiest form to sign.
Is this right for you?
If you own more than one property and aren’t sure whether your loans are cross-secured, it’s worth finding out before you need to know. A quick look at your loan and mortgage documents, or a call to your existing lender, will usually tell you.
If they are cross-secured and you’re planning to sell, refinance, or buy again in the next few years, unwinding the structure now, while nothing is urgent, is almost always easier and cheaper than doing it under pressure.
If you’re weighing this up against how your properties are held for tax and estate planning purposes, it’s worth reading trust and company structures for property investment alongside this one.
Frequently asked questions
How do I find out if my properties are cross-collateralised?
Check your loan agreement or mortgage documents for a list of securities against each loan. If more than one property is named as security for a single loan, or the same property secures more than one loan, you’re cross-collateralised. If you’re not sure, I can review your existing loan structure with you at no cost.
Does unwinding cross-collateralisation cost anything?
Usually yes, there can be discharge and new registration fees, and sometimes a valuation cost per property. These are generally modest compared to the flexibility gained, but I’ll always give you the actual figures before you decide, so it’s a clear-eyed decision rather than a guess.
Will restructuring to stand-alone loans affect my interest rate?
Not necessarily, and it’s often an opportunity to negotiate a better one. Because each loan is reassessed individually, this is a natural point to shop your rate across lenders rather than assuming your current bank remains the best option.
Can I unwind cross-collateralisation without selling any property?
Yes. Refinancing to separate the securities, keeping every property you currently own, is the most common approach. It typically involves new loan applications against each property individually rather than a single linked facility.