Medical professionals can often borrow more, skip Lenders Mortgage Insurance, and get faster approvals than other applicants, because many lenders view doctors, specialists and other registered medical professionals as low-risk, high-value clients.
If you’re a GP, specialist, surgeon or other medical professional thinking about buying, refinancing or investing, working with a broker who understands these lender policies can mean access to benefits that simply aren’t advertised on a bank’s website.
Why work with a mortgage broker as a medical professional
Time is one of your most valuable resources, and a mortgage broker helps simplify and streamline the loan process while offering guidance tailored to your career stage and goals.
Here’s how I typically support medical professionals:
- Save time: I compare dozens of lenders and home loan products, so you don’t have to.
- Access exclusive policies: I know which lenders offer special terms for medical professionals.
- Tailored advice: your loan is structured around your income, career stage and long-term goals.
- Better rates and terms: I negotiate directly with lender pricing teams to secure competitive outcomes.
Special lending benefits available to medical professionals
Lenders generally view medical professionals as low-risk, high-value clients, given stable, above-average incomes and strong long-term career prospects. That view translates into some genuine perks, outlined below.
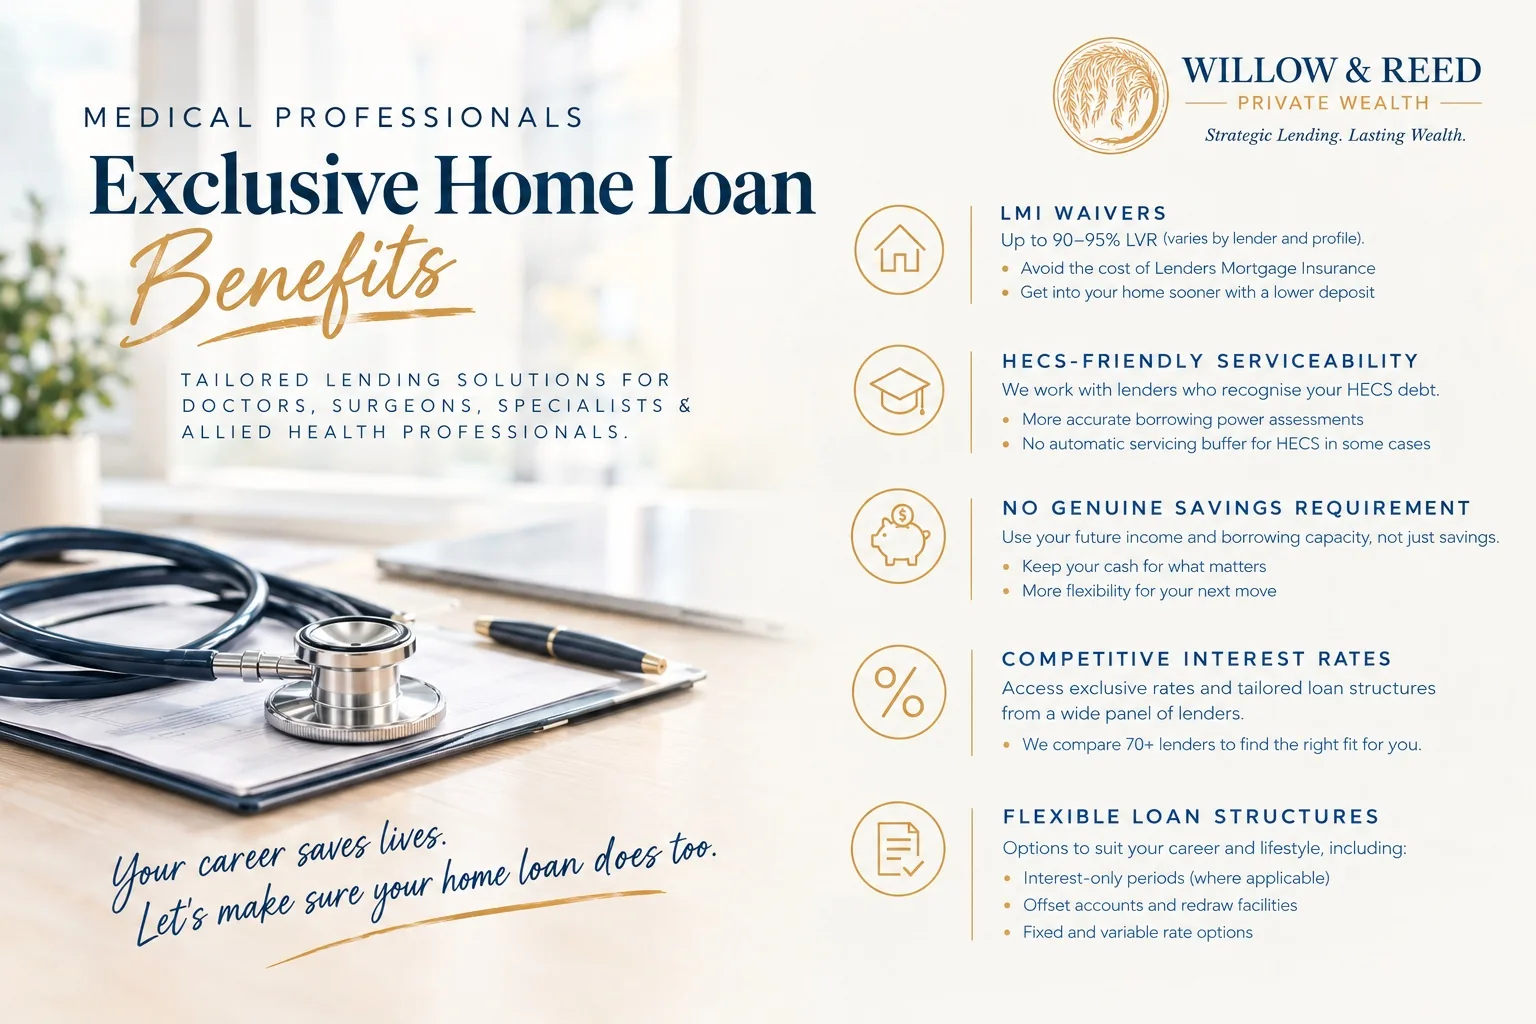
LMI waivers
Most borrowers pay Lenders Mortgage Insurance once they borrow more than 80 per cent of a property’s value. Many lenders waive LMI for medical professionals, even at a loan-to-value ratio (LVR) of 90 to 95 per cent. Depending on the purchase price, that can mean savings in the order of $10,000 to $40,000 or more. These figures are indicative only, vary by lender and loan size, and aren’t a guarantee for every applicant.
Higher borrowing capacity
Because of your earning potential and career stability, lenders are often more flexible when assessing your borrowing capacity as a medical professional. That can translate into a higher borrowing limit and better access to premium properties or investment opportunities.
Faster approvals and simpler paperwork
Some lenders offer priority processing for medical professionals, with simplified documentation requirements and quicker turnaround times, which matters when you’re competing for a property in a tight market.
Who qualifies for these benefits?
Eligibility varies by lender, but generally, if you’re registered with AHPRA or hold a recognised qualification in the medical field, you’re likely to qualify. Professions typically included are:
- General practitioners (GPs)
- Specialists (for example cardiologists and oncologists)
- Surgeons
- Dentists and orthodontists
- Anaesthetists
- Radiologists
- Psychiatrists
- Veterinarians
- Optometrists
- Pharmacists
- Chiropractors
Some lenders also consider allied health professionals and senior medical researchers on a case-by-case basis, so it’s worth checking your specific situation even if you’re not on this list.
Common lending scenarios I see with medical professionals
Medical careers rarely follow a simple, linear income pattern, and that’s exactly where a broker who understands the sector adds the most value. Some situations I regularly help clients work through include:
- Registrars and locums with variable income. Overtime, on-call loadings and locum shifts can make income look inconsistent on paper, even when overall earnings are strong. Knowing which lenders assess this kind of income favourably matters.
- Practice ownership and partnership buy-ins. Buying into a practice or clinic changes your income structure, and some lenders treat this very differently to standard employment.
- HECS or HELP debt. Many medical professionals still carry study debt years into their career. This affects borrowing capacity calculations differently across lenders, and some are more accommodating than others.
- Early career borrowing. Junior doctors and specialists still building their track record can sometimes access the same profession-based benefits as established consultants, depending on the lender’s policy.
None of these situations rule you out of the benefits above, but they do change which lender is the right fit, which is where tailored advice matters more than a generic comparison website.
Why work with me
I specialise in working with high-income earners who have complex financial profiles and busy, demanding lives. From your first home to a growing investment portfolio, my role is to make finance simpler, smarter and more rewarding, so you can stay focused on your career while building long-term wealth through property.
Frequently asked questions
Can medical professionals really avoid Lenders Mortgage Insurance?
Many lenders waive LMI for medical professionals, even at a loan-to-value ratio of 90 to 95 per cent, though the exact policy depends on the lender and your specific profession.
Which medical professions typically qualify for these lending benefits?
Lenders commonly include GPs, specialists, surgeons, dentists, anaesthetists, radiologists, psychiatrists, veterinarians, optometrists, pharmacists and chiropractors, with some also considering allied health professionals case by case.
Do I need to be registered with AHPRA to access these benefits?
Generally, yes. Most lenders require AHPRA registration or a recognised medical qualification to offer profession-specific benefits, though policies do vary.
Can medical professionals borrow more than other applicants?
Often, yes. Lenders tend to view medical professionals as low-risk given stable, above-average incomes, which can support a higher borrowing capacity than a standard applicant with similar income.
Is it only doctors who get these lending benefits, or do other health professionals qualify too?
It extends well beyond doctors. Dentists, vets, pharmacists, psychiatrists and several other registered professions are commonly included, and allied health professionals may be considered on a case-by-case basis.