If you earn $300,000 or more and you invest in property, the fastest way to build wealth isn’t necessarily picking a better suburb, it’s structuring your lending properly. The way your loans are set up, whether they’re interest-only or principal and interest, cross-collateralised or separate, fixed or variable, can make a meaningful difference to your cash flow and your flexibility over time.
I’m Durand, founder of Willow & Reed Private Wealth, and I work with high income professionals across Melbourne every week on exactly this. Here are five lending moves I discuss with clients who are serious about growing a property portfolio.
Why $300k plus earners need a different lending approach
Most lending advice online is written for someone buying their first home. If you’re earning $300,000 or more, your situation is different. You likely have more borrowing capacity, more complex income (bonuses, trusts, company structures or multiple employers), and more at stake if your loans aren’t structured well.
A generic “get the lowest rate” approach can actually cost you money over time if it ignores tax deductibility, cash flow timing and how easily you can move properties in and out of your portfolio. The five moves below are the ones I see make the biggest practical difference.
1. Use interest-only loans strategically
An interest-only loan means your repayments only cover the interest charged, not the loan balance itself, for a set period, commonly one to five years. For an investment property, this can improve cash flow in the short term and keep more of your income available for further investing, since the interest on an investment loan is generally tax deductible while the loan is used for income producing purposes.
Interest-only lending isn’t right for everyone. Because you’re not paying down the principal, you’re relying more heavily on capital growth to build equity, and your repayments will step up once the interest-only period ends. I usually recommend clients treat an interest-only period as a deliberate, time-limited strategy, with a clear plan for what happens when it expires, rather than a default setting.
2. Keep your loans separate, don’t cross-collateralise
Cross-collateralisation happens when a bank uses more than one property as security for a single loan, or links several loans together across your properties. Lenders often suggest it because it gives them more security, but it can work against you as an investor.
When your properties are cross-collateralised, selling or refinancing just one of them usually means the lender has to reassess your entire security pool, which slows things down and reduces your flexibility. I generally recommend structuring each property with its own separate loan and, where it makes sense, its own lender. It takes a little more coordination up front, but it gives you far more control later, particularly if you want to sell one property without disturbing the others.
3. Release equity carefully, not aggressively
As a property grows in value and you pay down your loan, the gap between what it’s worth and what you owe, your equity, grows too. Many investors use this equity as a deposit for their next purchase, rather than saving a new deposit from scratch.
The key word is carefully. Releasing equity is a genuinely useful way to keep building a portfolio without draining your savings, but stretching your borrowing too far can leave you exposed if rates rise or a property sits vacant for a stretch. I work through a conservative equity release with clients, one that funds the next purchase without compromising your buffer or your lifestyle.
4. Match your loan structure to your strategy
Before you lock in a rate, it’s worth asking what the property is actually for. Are you chasing capital growth or rental yield? Is this a long-term hold or something you expect to sell within a few years? The answer should shape your loan structure, not the other way around.
- Variable rates generally suit investors who want flexibility, such as the ability to make extra repayments or use an offset account.
- Fixed rates can suit investors who want certainty over repayments for a set period, though they’re usually less flexible if your plans change.
- Offset accounts reduce the interest you’re charged by offsetting your loan balance against savings held in a linked account, without paying down the loan itself, which can matter for tax purposes on an investment property.
- Interest-only versus principal and interest should reflect your cash flow needs and how long you plan to hold the property, not just what feels cheaper month to month.
If you’re weighing up offset accounts against paying extra off your loan, our offset versus redraw guide goes into more detail.
5. Review your lending every 12 to 18 months
Property markets move, interest rates move, and lending policies move. A loan structure that suited you two years ago might not be the most competitive or most efficient option today. I recommend a proper review of your lending at least once every 12 to 18 months, or sooner if your income, your goals or interest rates change materially.
A review isn’t just about chasing a lower rate. It’s a chance to check whether your structure still matches your strategy, whether you should be separating a cross-collateralised loan, or whether it’s time to release some equity for your next purchase. If you haven’t reviewed your lending in a while, our article on what to consider when refinancing is a good place to start.
Where to start
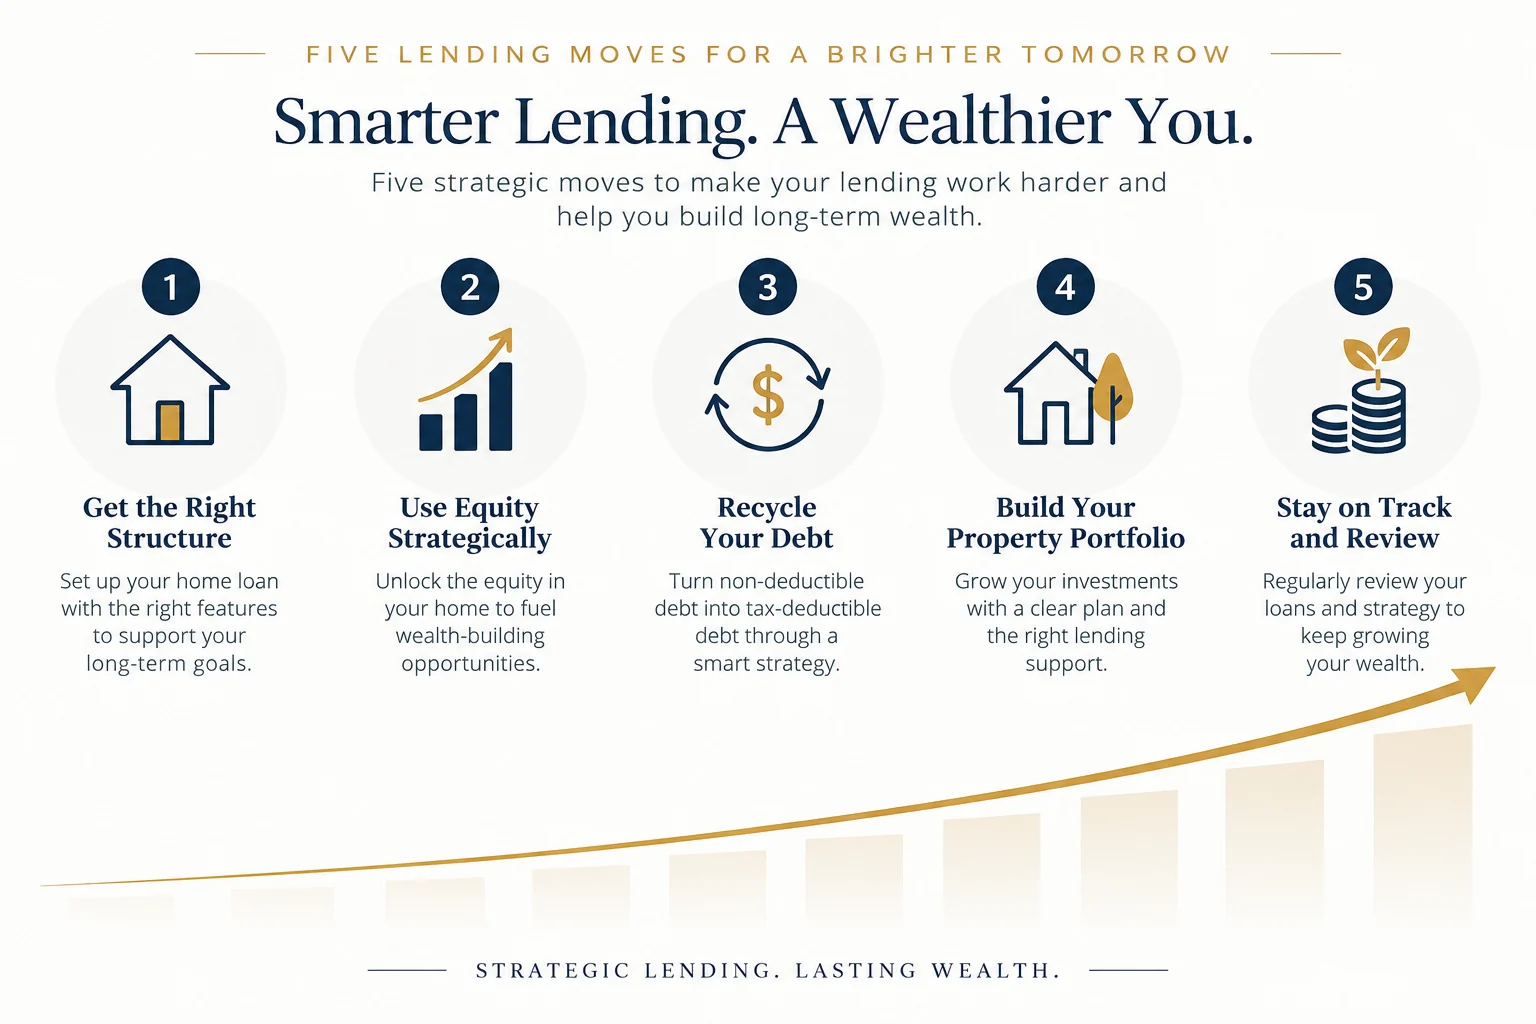
None of these five moves work in isolation. Interest-only lending, separating your securities, releasing equity carefully and matching structure to strategy all connect to each other, and to the bigger picture of how you’re building your portfolio. That’s why I sit down with clients and map the whole lending structure, not just the next loan.
If you’re earning $300,000 or more and want your lending to work as hard as you do, let’s talk about your current structure and where it could improve.
Frequently asked questions
What is an interest-only loan and why do high income investors use it?
An interest-only loan means your repayments cover only the interest for a set period, usually one to five years. High income investors often use this structure to improve cash flow in the short term and free up funds for further investing, since interest on an investment loan is generally tax deductible.
What does cross-collateralising properties mean?
Cross-collateralisation is when a lender uses more than one property as security for a loan, or links loans across your properties together. It can reduce your flexibility later, since selling or refinancing one property may require the lender to reassess your whole security pool.
How often should I review my investment loans?
I recommend reviewing your lending structure at least once every 12 to 18 months, or sooner if your income, your goals or interest rates change significantly.
Is it a good idea to release equity to fund a new property purchase?
It can be, provided it’s done carefully. Equity release lets you use the growth in an existing property as a deposit for your next purchase, but over-leveraging can leave you exposed if rates rise or a property is untenanted for a period, so a conservative approach matters.
Should I choose a fixed or variable rate for an investment loan?
It depends on your strategy. Variable rates generally suit investors who want flexibility, such as extra repayments or an offset account, while fixed rates suit those who want repayment certainty for a set period.