With spring here and the property market picking up across Melbourne, it’s a natural moment to look at your home loan with fresh eyes.
Rates, lender policies and your own situation all shift over time. A loan that suited you two or three years ago might not be the best fit today. You could be paying more than you need to, missing out on a better offset setup, or sitting on equity you could put to work.
This isn’t a sales pitch for refinancing. Plenty of the reviews I do end with “your loan is fine, leave it where it is”. The point is knowing that, rather than assuming it.
Why spring is worth a check
Spring is when a lot of my clients start planning. Some are thinking about upgrading, some are eyeing an investment property, and some just want to get ahead before the end of the year. All of those plans depend on what your current loan is doing, and how much room it gives you.
It’s also a good moment because lenders compete hardest for new customers. The rate you were offered when you first settled is often not the rate a new borrower would get today for the same loan. Lenders rarely call to tell you that.
What I look at in a home loan review
A proper review isn’t just comparing your rate with an ad. It usually covers three things.
Your rate against your loan size and LVR. Lenders price loans by how much you borrow and how much equity you hold. If your balance has come down or your property has gone up in value, you may now sit in a better pricing band than when you started. That’s worth asking about.
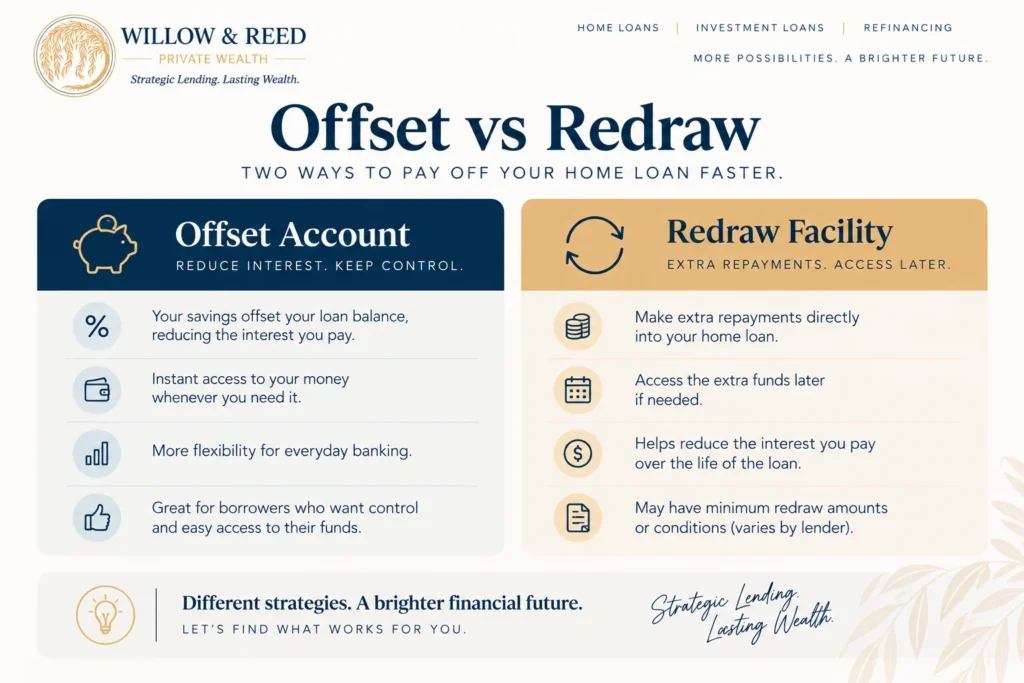
Your structure. Is your offset account doing real work, or is it sitting near zero? Are you split between fixed and variable in a way that still makes sense? Is a fixed period about to end, with your loan about to roll onto a higher default rate? Small structural changes can make a bigger difference over time than a small rate cut.
Your plans for the next few years. If you’re planning to renovate, invest or upgrade, your loan should be set up to help, not get in the way. That might mean releasing equity, separating loans for different purposes, or keeping things flexible so you don’t pay break costs later.
Signs your loan may have drifted
You don’t need a review every year, but these are worth paying attention to:
- You haven’t spoken to your lender or broker about your rate in more than two years.
- A fixed rate period ends in the next six months.
- Your offset or savings balance has grown, but your loan was never set up to use it properly.
- Your income, family or plans have changed since you settled.
- You’ve been thinking about renovating, investing or upgrading, but aren’t sure what you can borrow.
If two or more of these sound familiar, a review is likely to be worth your time.
What a review won’t do
A review doesn’t commit you to anything, and it doesn’t mean switching lenders. Sometimes the best result is a phone call to your existing lender to ask for a sharper rate. Sometimes it’s a small change to how your offset or splits are set up. Refinancing only makes sense when the savings clearly outweigh the costs of switching. I’ll show you the numbers either way.
If you’d like a feel for it first, the refinance calculator and the offset calculator are good starting points.
Is this right for you?
If it’s been a while since anyone looked at your loan, or your plans for the next few years have changed, it’s worth a conversation. There’s no cost and no obligation. I’ll look at what you have now, what’s available across more than 70 lenders, and whether a change is genuinely worth making.
If you’re already thinking about a refinance, my refinancing page explains how I approach it. If you’re more interested in using the equity you’ve built, start with equity release.
Frequently asked questions
How often should I review my home loan?
Every two years is a good rhythm for most people, or sooner if your fixed rate is ending, your income changes or you’re planning a big purchase.
Will a home loan review affect my credit score?
No. A review is a conversation about your current loan and options. A credit check only happens if you decide to apply for a new loan.
Is it worth asking my current lender for a better rate first?
Often, yes. Lenders will sometimes reprice a loan to keep a good customer. I can help you work out what to ask for, based on what other lenders are offering for a similar loan.
What does a review cost?
Nothing. Mortgage broking is typically paid by the lender if a new loan settles, and there’s no obligation to change anything after the review.