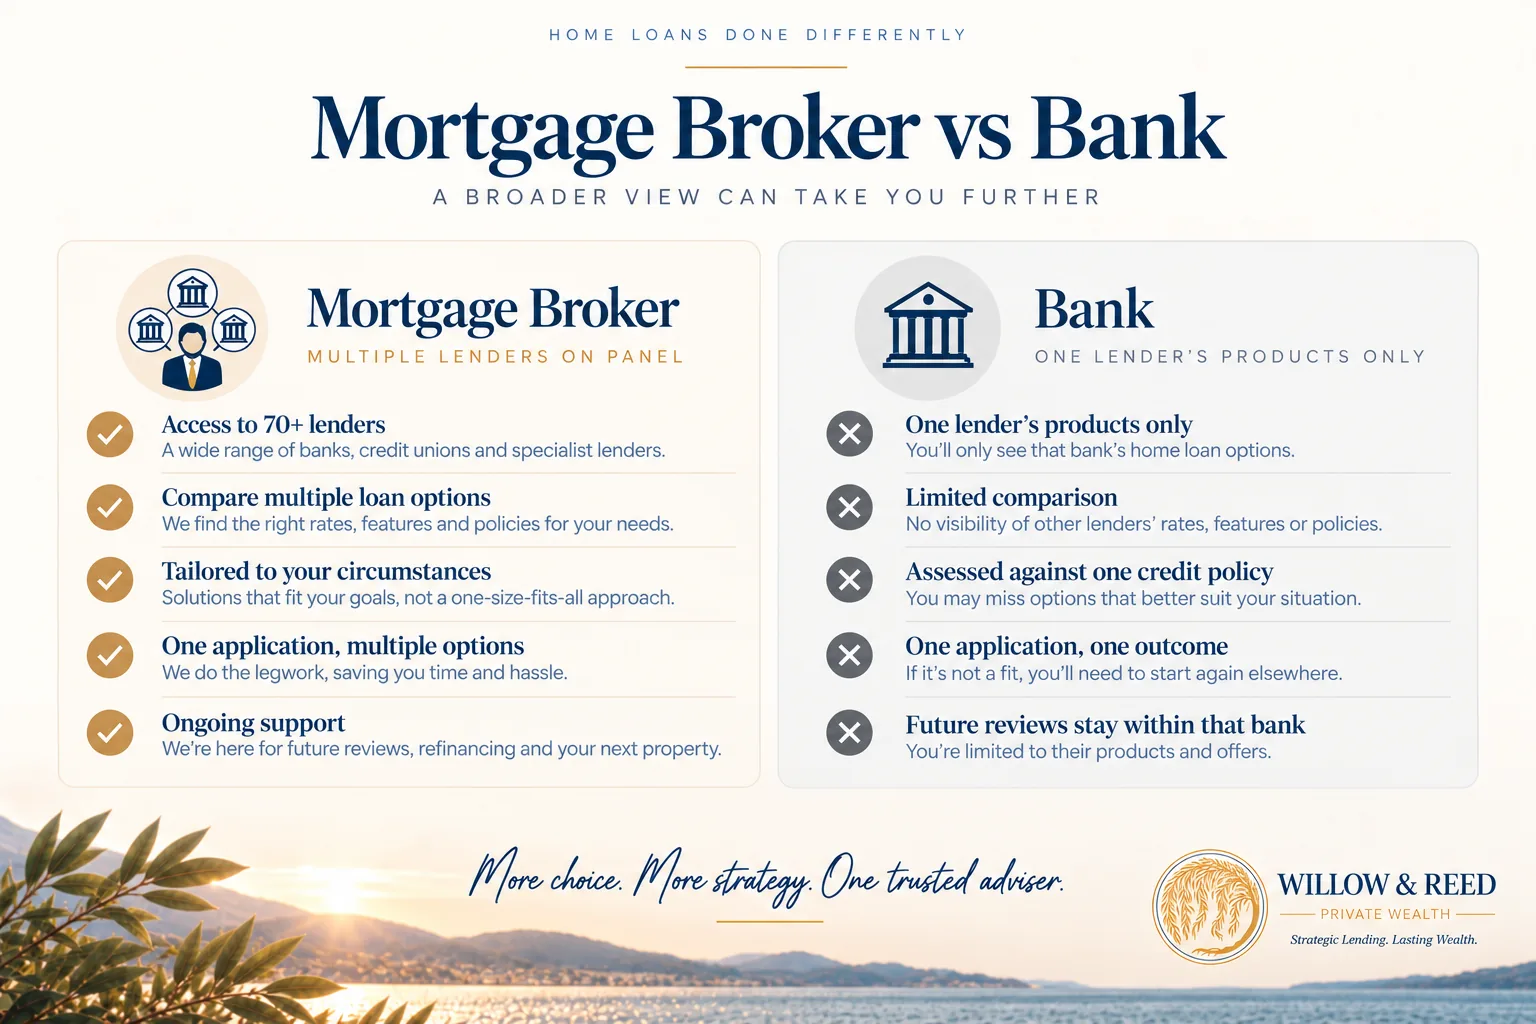
A mortgage broker will almost always give you more loan options and a more strategic result than walking into a bank alone, because a broker like me can compare over 60 lenders against your situation instead of pitching you the one product a bank branch is paid to sell.
For professionals and families juggling busy careers, investment plans and more complex income, that difference in choice, advice and ongoing support is usually worth far more than the convenience of banking with a familiar name.
Banks can only sell you their own products
When you walk into a bank, you are shown that bank’s home loans and nothing else. Even a bank’s own in-house broker is still limited to that one lender’s policies, rates and appetite for risk.
I work with over 60 lenders, from the major banks through to niche and non-bank lenders who specialise in more complex or strategic borrowing needs. That range means I can match your situation to the lender most likely to say yes on the best terms, rather than fitting your finances into whatever one bank happens to offer that month.
A broker builds you a lending strategy, not just a loan
Getting a loan approved is only part of the job. The bigger question is how that loan fits into your broader financial picture over the next five, ten or twenty years.
I take a holistic view of your finances whether you are:
- Upgrading your family home
- Refinancing to improve cash flow
- Investing in property
- Managing multiple loans across a growing portfolio
That means the advice you get is built around your goals, not around a single product a bank teller needs to sell this quarter.
Lender policy knowledge saves you time and unnecessary credit checks
Lender policies vary far more than most people expect. What one bank declines outright, another may approve without hesitation, particularly for:
- Professionals with complex or non-standard income
- Business owners and self-employed borrowers
- Investors with multiple properties or trust structures
Knowing which lenders are genuinely comfortable with your situation before you apply means fewer wasted applications, fewer credit enquiries on your file, and a faster path to approval.
You get ongoing support, not a one-off transaction
Walk into a bank branch and you might deal with a different person every time you call. As a broker, I stay with you well after settlement, reviewing your rate, flagging refinancing opportunities, and helping you adjust your strategy as your income, family and goals change.
That relationship matters most when life gets more complicated, not less, which is exactly when a lot of professional families need the most support.
There is no cost to use a broker
My services cost you nothing directly. I am paid by the lender once your loan settles, and my legal and professional duty is to act in your best interest throughout the process, not the lender’s.
In practice, that means you get expert advice and a properly structured loan, without paying extra for the privilege.
What to check before choosing a mortgage broker
Not all brokers offer the same depth of service, so it’s worth asking a few questions before you commit to working with someone:
- How many lenders are on their panel, and does that panel include lenders suited to your income type
- Whether they hold their own Australian Credit Licence (ACL) or operate as a credit representative under one, and who that licensee is
- Whether they have genuine experience with clients in your situation, whether that’s a business owner, an investor, or a professional with complex income
- Whether they offer ongoing reviews after settlement, or treat the loan as a one-off transaction
A broker who can answer these clearly, and who takes the time to understand your goals rather than rushing to a product, is generally the one worth working with.
Frequently asked questions
Is it more expensive to use a mortgage broker than going straight to a bank?
No. Brokers are paid a commission by the lender once your loan settles, so there is no direct cost to you for using a broker, and the interest rate you’re offered is not marked up to cover it.
Can a mortgage broker access better rates than I could get myself at a bank?
Often, yes. Brokers deal with lender pricing teams regularly and know which lenders are competing hardest for certain types of borrowers, so I can negotiate on rate and terms in ways an individual walking into a branch usually cannot.
Why would a bank decline me when another lender would approve the same loan?
Every lender has its own risk appetite and assessment rules, particularly around income type, employment structure and existing debt. A broker who knows those differences can match your application to the lender most likely to approve it on good terms.
Do I need to have a straightforward income to work with a mortgage broker?
Not at all. Brokers are often most valuable for professionals, business owners and investors with more complex income, multiple properties or trust structures, precisely because that’s where bank policy varies the most.
Does a mortgage broker help after my loan has settled?
Yes. I continue to review my clients’ loans after settlement, watching for rate changes and refinancing opportunities as their circumstances and the market evolve.